• 01772 888 778
  • info@xyfil.com
  • Unit 1 & 2, Durton Lane Business Park, Preston, PR3 5LR

Author Archives: Hannah Rubery

Digital Duty Stamps: What to Ask Your Manufacturer Before January 1st

From January 1st, 2027, only digital duty stamps can go on vaping products in the UK. Transitional stamps had a short life by design, and their window is now closing. For brand owners, that makes the next few weeks a useful checkpoint. If your manufacturer applies your stamps, the switch happens on their line and under their approvals. So it's worth asking a few clear questions now, while there's plenty of time to act on the answers.

This guide gives you seven of them. Each one comes with a note on what a good answer sounds like. You can use them with your current manufacturer, or with any partner you're considering.

Key takeaways

  • From January 1st, 2027, only digital duty stamps can be affixed. You can buy transitional stamps until November 30th and affix them until December 31st, 2026, according to HMRC's key dates.
  • Whoever applies a digital stamp must activate it at that moment. After that, operators scan it at set points.
  • Your manufacturer's approvals, data handling and stamp controls now shape how smoothly your stock reaches the shelf.
  • Seven simple questions show whether your set-up is ready for the switch.

Why the switch to digital duty stamps is a good moment to check in

Since Vaping Products Duty went live on October 1st, every new duty-liable product released for UK sale has needed a stamp. Until now, many brands have used transitional stamps. These carry physical security features only, so nobody scans them.

Digital stamps add a scannable code. Whoever applies the stamp must activate it at the point of affixing and record data about the product. After that, operators scan it again at set points, including release for consumption, as HMRC's stamp guidance sets out.

In short, more of the work now sits with whoever affixes your stamps. That's good news if you have a well-prepared partner, because the extra steps happen out of sight. It also means a quick conversation now can save a scramble in January. Our guide to digital vs transitional vape duty stamps covers the mechanics in full. Here, we focus on the questions.
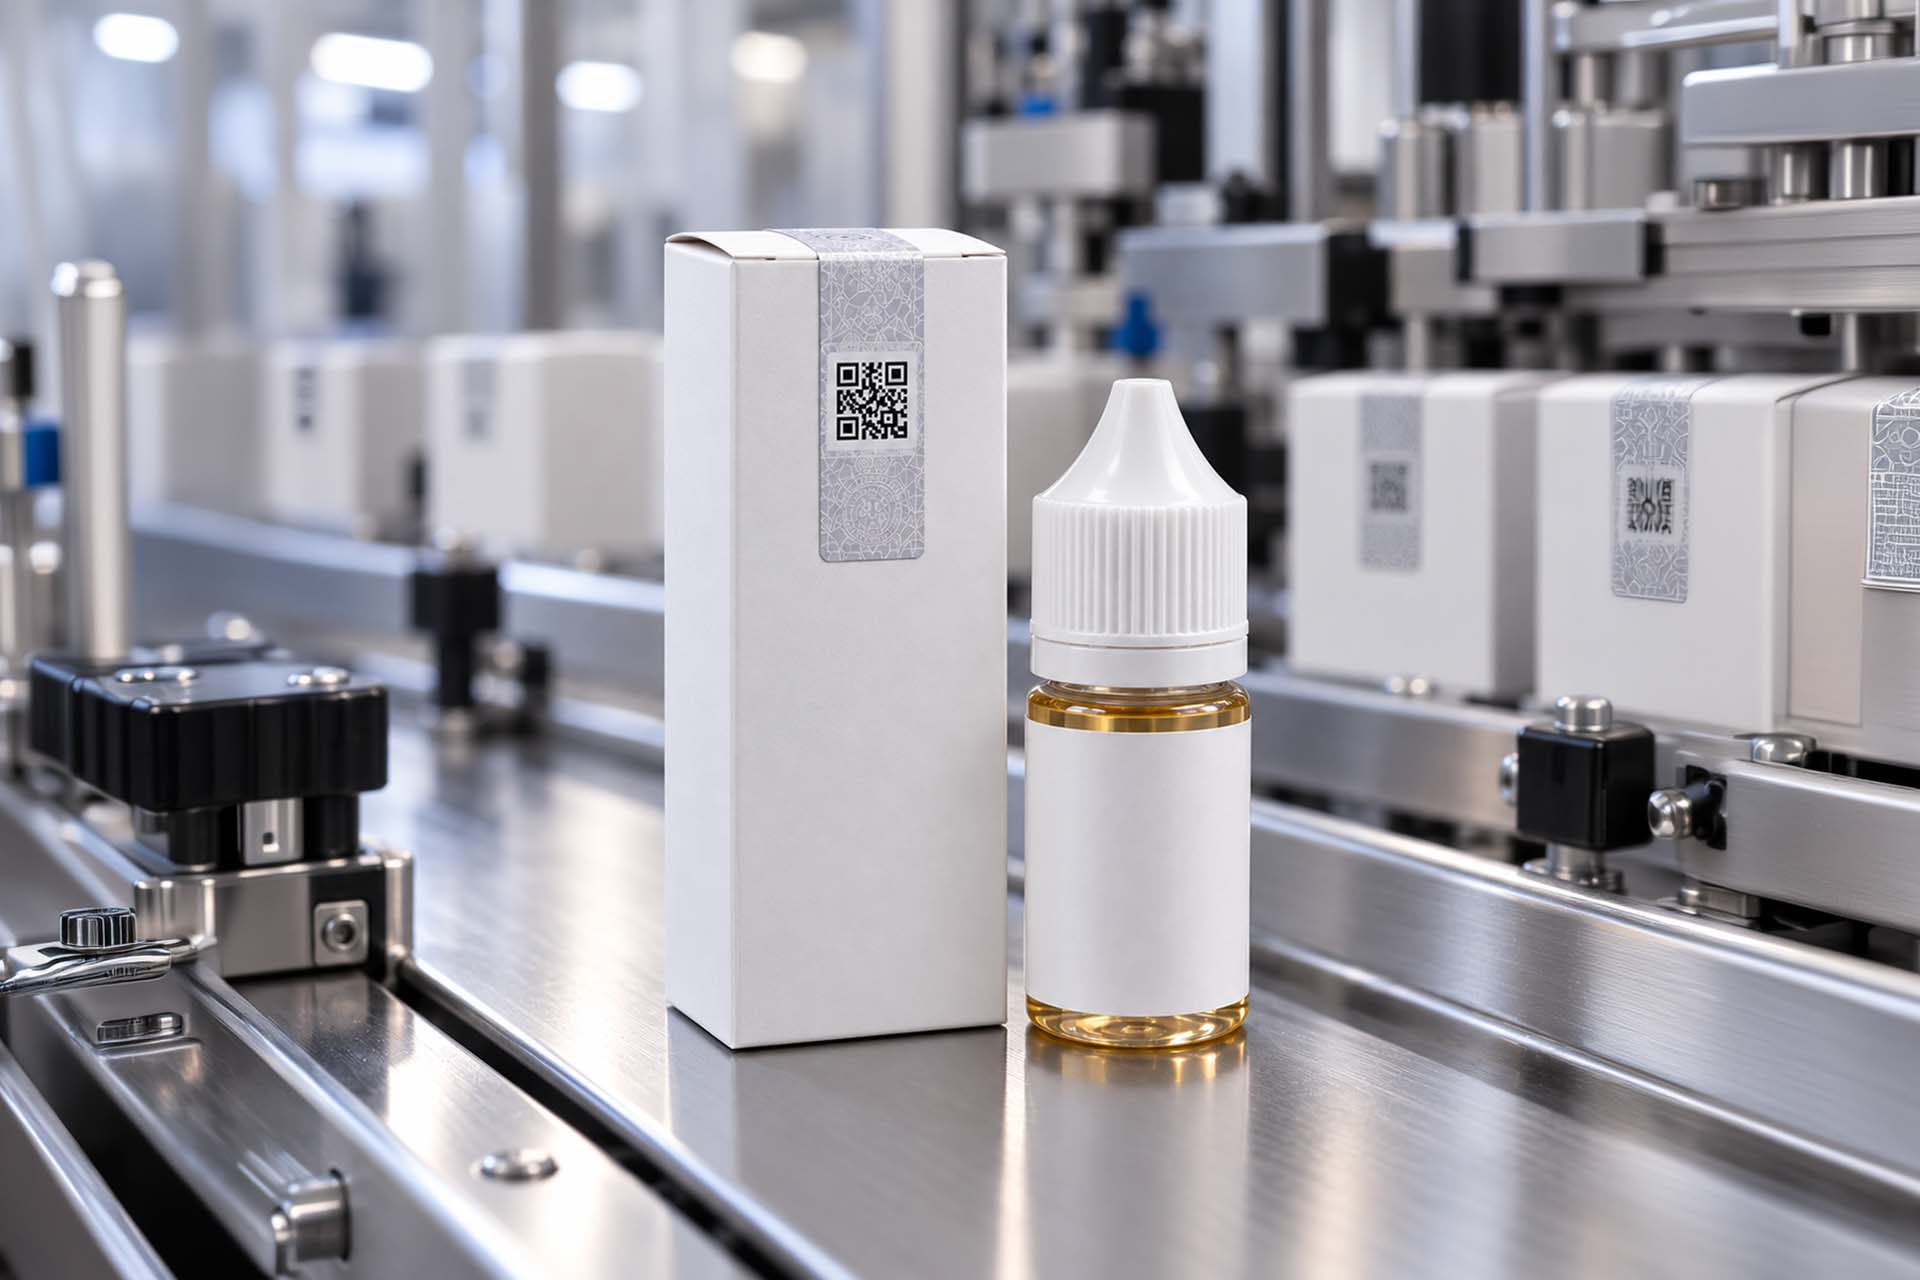
Digital vape stamp on E-liquid products

Seven questions to ask your manufacturer about digital duty stamps

1. Which approvals do you hold, and which ones cover stamping?

Only HMRC-approved purchasing operators can buy duty stamps. That means UK manufacturers, warehousekeepers and UK representatives. They order through the appointed supplier's secure platform.

So start with the basics. Ask which approvals your manufacturer holds, and whether they include stamp affixing at their own site.

A good answer: a clear list of approvals, plus a plain explanation of who buys, holds and applies your stamps.

2. Are you already applying digital stamps?

Digital stamps have been on sale since September 1st, 2026. Some operators started with them straight away, while others used transitional stamps first. Either approach works until December 31st.

From January 1st, however, every stamp needs activating as it goes on. Each activation records details such as the time, date and address of affixing, the operator and the product. Ask whether your manufacturer has already run digital stamps through its line, or when it plans to start.

A good answer: a firm start date, and a trial run before your first January batch.

3. How will you set up my product data?

Every SKU needs a record in the stamp supplier's system before its stamps can go live. HMRC's guidance lists ten fields. They include the GTIN barcode, volume to the nearest 0.1ml, brand, flavour, product type and nicotine content. Nicotine products also need their ECID or GBID.

Ask who builds these records, and what they need from you. When a brand moves its production to us, product data is one of the first things we look at. Every stamp depends on it, so getting it right early keeps the first run on schedule.

A good answer: a simple template, one point of contact and a check before the first run.

4. Who generates aggregation codes, and how do you record sales?

Digital stamps link to higher-level packaging through aggregation codes. These connect each stamped unit to its carton, master case and pallet. Either the manufacturer or the importer can generate them. Operators then report each link through an API built on the GS1 EPCIS standard.

There's a useful shortcut here too. At the final exit-to-market scan, an operator can declare a sale event for an aggregate code. That status then applies to every code linked beneath it, so nobody needs to scan each unit one by one.

A good answer: a named owner for aggregation, and a process that records cases and pallets rather than single units wherever it can.

5. Where do you hold my stamps, and how do you reconcile them?

HMRC expects operators to keep stamps in secure storage with access controls. It also expects routine reconciliations of stamps ordered, received, used, returned and destroyed. On top of that, operators need incident processes for loss, theft, damage and discrepancies.

Digital stamps add one more date to track. Operators must activate stamps within 12 months of receiving them, or a penalty may apply.

A good answer: stamps held securely in the UK, a reconciliation after every run, and records you can see on request.

6. What happens to any transitional stamps left after December 31st?

Transitional stamps can't go on after December 31st, 2026. So it's worth asking whether your manufacturer expects any to be left over, and what it plans to do with them.

Destroying unused stamps also follows a set process. Operators must tell HMRC the method, time, date and location before they destroy any stamps.

A good answer: an ordering plan that keeps leftovers low, and a clear process for any that remain.

7. Does your stamp purchase limit cover my volumes?

HMRC sets each operator a purchase limit over a rolling three-month period. Operators may go over it by up to 30%. They can also ask for a rise if they show a business need.

So if you plan to grow, launch new flavours or move more production across, share your forecast early. Our duty stamp timeline shows how far ahead each step needs to start.

A good answer: confirmation that your volumes fit, plus a plan for busy months.
Industrial printing machine printing labels in batches

What good answers have in common

Look back over the answers, and a pattern usually appears. Strong partners answer quickly and specifically. They name who does each step. They show you records instead of describing them. And they treat your forecast and product data as shared work, with clear deadlines on both sides.

If a few answers feel vague, that's fine. It simply shows you where to ask a follow-up question before January. For a wider view of the partnership, see our five signs your manufacturer may be holding your brand back.

How Xyfil answers these questions

We've manufactured e-liquid in Preston since 2014. Our VPD approvals cover production, import, warehousing, duty stamp affixing and UK duty representation. As a result, buying, holding and applying your stamps all happen within one approved business.

We apply both transitional and digital duty stamps today, so you can move to digital whenever it suits your range before January 1st. We've built the stamp workflow into how we plan every production run. Your stamps stay in our secure UK custody, and every run closes with a reconciliation pack. Each stamp then ties back to its HMRC dataset and a GS1-aggregated batch record.

We can also take on your packaging artwork, so the stamp has a clear home on your pack from the first print. For artwork questions, our guide to designing packaging for stamp integrity is a good next read. And if you import, our comparison of stamping and fulfilment routes shows how each route handles the move to digital.

Digital duty stamp FAQs

When do digital duty stamps become mandatory?

From January 1st, 2027, only digital duty stamps can be affixed to vaping products in the UK. Approved businesses can buy transitional stamps until November 30th, 2026 and affix them until December 31st, 2026. Digital stamps have been on sale since September 1st, 2026, so operators can switch sooner.

Do I need my own HMRC approval to use digital duty stamps?

Not if a partner applies them for you. Only HMRC-approved manufacturers, warehousekeepers and UK representatives can buy duty stamps. If your manufacturer holds stamp approvals, it buys, activates and applies the stamps on your behalf. You'll still need to supply accurate product data for each SKU.

What data does a digital duty stamp need?

Each SKU needs a record with ten fields. These include the product name, description, GTIN barcode, volume to the nearest 0.1ml, brand, flavour and product type. The record also covers nicotine content and a JPEG image. Products containing nicotine need their ECID or GBID notification number too.

Can retailers scan digital duty stamps yet?

HMRC says retailers and consumers will be able to scan digital stamps to check authenticity in due course. For now, approved operators scan them at affixing, during permitted duty-suspended movements and at release for consumption. Codes work with standard scanners, and phones can read them through an app.

Get your range ready for digital duty stamps

The move to digital stamps is a chance to tidy your product data and confirm your stamping set-up, well ahead of the new year. Send us your SKU list and a short note on how your range is made and stamped today. We'll show you how it moves onto digital stamps, and what we'd need from you to get started.'ll show you how it moves onto digital stamps, and what we'd need from you to get started.
Get in touch with the team.

Vaping Products Duty Is Live: What’s Changed, What Hasn’t, and What Comes Next

Vaping Products Duty went live on the 1st of October, 2026. The countdown is over, and stamped stock is already moving through the supply chain. Yet for most brand owners, the questions have simply changed shape. What actually changed on day one? What stays exactly as it was? And which dates belong in your diary between now and next spring?

This guide answers all three. It's written for brand owners, importers and anyone who relies on a manufacturing partner to stay compliant.

What changed on October 1st 2026?

Three things changed at once: the duty, the stamp and the paperwork behind both.

The duty now applies to every new unit

Vaping Products Duty now applies at £2.20 per 10ml. That works out at 22p per ml, whether the liquid contains nicotine or not. It covers all vaping liquid manufactured in or imported into the UK from October 1st. The one exception is stock held in duty suspension, such as an approved excise warehouse.

HMRC-approved manufacturers, importers and warehousekeepers pay the duty. Whether they pass that cost on to retailers and consumers is a commercial decision for each business. HMRC said as much in its go-live announcement.

Duty stamps have reached the shelf

Before October 1st, no stamped product could reach the UK market. Now, yellow or red tamper-evident stamps have started to appear on retail packs. Every new duty-liable unit released for UK sale needs one on its outermost retail packaging.

Approval became a legal line

Manufacturing vaping products without HMRC approval is now unlawful. HMRC's go-live notice lists civil penalties, seizure of goods and equipment, and criminal prosecution as possible consequences. So if you manufacture, import or store vaping products yourself, your approvals need to be in place today. And if a partner does that work for you, their approvals carry the same weight as your own.

Every movement now leaves a record

Approved manufacturers, importers and warehousekeepers now report how vaping products move through the supply chain. HMRC also expects records for every batch, stamp and movement under duty suspension. As a result, your paperwork matters as much as your production line. If a partner holds your stock, ask how they reconcile it each month.

Monthly returns start in November

For approved manufacturers like Xyfil, you now file a monthly return through HMRC's Manage your Vaping Products Duty online service. The first return falls due on 7 November 2026. After that, payments fall due by the 15th of each month. You'll also need to file a nil return for any month without production. In practice, your duty records need to reconcile from the first week of October onwards.

What hasn't changed

Plenty stays the same. That matters just as much for your planning.

  • The rate stays flat. Nicotine strength and format don't change the duty per ml. A 2ml pod carries 44p, and a 10ml bottle carries £2.20.
  • VAT still applies. VAT continues to apply to vaping products, just as before.
  • Duty suspension still changes timing only. Stock in duty suspension waits until release, and then the full duty falls due. Neither suspension nor any other route reduces the amount you owe.
  • Existing stock keeps its runway. Wholesalers and retailers can sell eligible unstamped stock they already hold until the 31st of March 2027.
  • Shops still don't need approval. Businesses that only sell or distribute duty-paid stock don't need to apply.
  • Your product rules still stand. MHRA notification and labelling rules apply as before. In fact, the stamp system builds on them, because nicotine products need their ECID or GBID in the stamp data.

What the next six months look like

From here, the dates arrive in a steady run. Most of them need weeks of preparation, so it helps to see them together.

  • 7th of November 2026: the first monthly duty return is due.
  • 30th of November 2026: the last day to buy transitional stamps.
  • 31st of December 2026: the last day to affix transitional stamps.
  • 1st of January 2027: digital stamps become mandatory for new products made in or imported into the UK.
  • 31st of March 2027: the last day to sell eligible unstamped stock.
  • 1st of April 2027: every vaping product outside duty suspension must carry a valid stamp.

Three of those dates cover the move from transitional to digital stamps. Our guide to digital vs transitional vape duty stamps explains what that switch means for your packs. Beyond that, each date depends on work that starts well before it. Our duty stamp timeline shows how far ahead stamp orders, product data and production slots need to move.

Two things to watch alongside the dates

First, packaging rules may move again. The Department of Health and Social Care has consulted on plain packaging, limits on flavour descriptors and keeping vapes out of sight in shops. That consultation closed on the 2nd of October 2026, so a government response could follow. If you're planning new artwork for 2027, keep some room for change.

Second, enforcement is scaling up. The government has committed £30 million a year until 2028–29 to Trading Standards, Border Force and HMRC. That funding targets illicit and underage sales of tobacco and vapes. In due course, retailers and consumers will also scan digital stamps to check authenticity. As a result, a clean stamp record will protect your stock long after it leaves the warehouse.

The March deadline deserves its own plan

The 31st of March 2027 cut-off affects anyone with unstamped stock still in the market. For brand owners, the real question is how much of that stock will sell through in time. It's worth a plan of its own, and we'll look at it in more detail closer to the date. For now, check where your unstamped stock sits and how fast it moves.

Where Xyfil fits now the duty is live

We've manufactured in Preston since 2014. Our VPD approvals cover production, import, warehousing, stamp affixing and UK representation. So whichever route your product takes, the duty, the stamps and the records sit inside a process we already run.

If we manufacture for you, nothing changes on your side. Meanwhile, if you import, finishing part-finished goods in the UK keeps your duty point at release and your stamps in secure UK custody. For a side-by-side view of every option, see our comparison of stamping and fulfilment routes.

Vaping Products Duty FAQs

Is Vaping Products Duty now in force?

Yes. It has applied since October 1st 2026, at 22p per ml of vaping liquid, with or without nicotine.

Can shops still sell unstamped vapes?

Yes, for now. Wholesalers and retailers can sell eligible unstamped stock they already held until the 31st of March 2027. From the 1st of April 2027, every product outside duty suspension needs a valid stamp.

When is the first Vaping Products Duty return due?

The first return is due on the 7th of November 2026. Payments then fall due by the 15th of each month, and months without production still need a nil return.

Do retailers need HMRC approval for Vaping Products Duty?

No. Businesses that only sell or distribute duty-paid stock don't need approval. However, they do need to check that new stock carries a valid stamp.

Map your next six months with us

The duty is live, but the busiest stretch of the transition still lies ahead. Send us your current route and your key dates, and we'll map where each one lands for your stock.

Book a VPD planning call with the team →

Digital vs Transitional Vape Duty Stamps: What Brand Owners Need to Know

Vaping Products Duty (VPD) applies from 1 October 2026. From then, every vaping product made in or imported into the UK needs a vaping duty stamp before sale. However, the scheme starts with two different stamps, and they follow very different timelines. For brand owners, that difference shapes packaging, stock planning and even your route to market. So here's a clear guide to both stamp types, what each one means for your brand, and how to keep your stamping covered.

What a vape duty stamp does

Vaping Products Duty adds £2.20 of excise duty for every 10ml of vaping liquid. The duty stamp works alongside it as visible proof. It's a secure label with physical security features, and it helps retailers, enforcement teams and HMRC spot legitimate stock.

The stamp goes on the outermost retail packaging. That means the box, or the bottle itself if you sell it without a box. It also has to seal the pack, so nobody can open it without damaging the packaging or the stamp. Stamps can't be reused, either.

Across the trade, people often call this "vape stamp duty". Officially, the rules sit under HMRC's Vaping Duty Stamps Scheme (VDS). They cover every e-liquid, whether it contains nicotine or not.

Transitional vs digital duty stamps: the core difference

Both stamps do the same basic job. The real difference shows up after the stamp goes on.

The transitional duty stamp

The transitional stamp carries physical security features only. It has no scannable code, so nobody scans it at any point in the supply chain. HMRC introduced it as a bridge, giving production lines time to adapt before the digital system takes over.

The digital duty stamp

The digital stamp carries the same physical features, plus a unique scannable code. Whoever applies it must activate it at the moment of affixing. That activation links each stamp to a set of product and operator details. After that, the stamp gets scanned again at set points, including permitted movements under duty suspension and release for consumption.

In practice, the digital stamp turns every retail unit into a traceable record. As a result, HMRC can follow a product from the production line to the shelf.

FeatureTransitional stampDigital stamp
Physical security featuresYesYes
Scannable unique codeNoYes
Activation when affixedNoYes, by the affixing operator
Scanned through the supply chainNoYes, at affixing, permitted duty-suspended movements and release
Linked product dataNoYes, from the SKU record
Aggregation codes for cartons and palletsNoYes
Long-term roleBeing phased outThe permanent standard

Transitional stamp deadlines and the dates to plan around

The transitional stamp has a short, fixed life. Approved businesses can buy transitional stamps until 30 November 2026 and affix them until 31 December 2026. Digital stamps have been available since 1 September 2026. Then, from 1 January 2027, digital becomes the only stamp anyone can affix.

Meanwhile, a separate clock runs for older stock. Retailers and wholesalers can keep selling eligible unstamped stock they already hold until 31 March 2027. After that, every vaping product outside duty suspension needs a stamp.

You may still see older dates online. HMRC's first timetable closed transitional stamp sales on 31 August 2026. It then extended the window following industry feedback, so the dates above are the current ones.

What brand owners need to know

You probably won't buy stamps yourself

Only HMRC-approved purchasing operators can buy stamps. That means UK manufacturers, warehousekeepers and UK representatives, ordering through the appointed supplier's secure platform. HMRC also caps each operator's purchases over a rolling three-month period. So unless you hold those approvals yourself, your stamps come through a partner. For that reason, your partner's approvals, limits and stamp controls matter as much as your own planning.

Your product data becomes part of the stamp

Digital stamps link to product records in the supplier's system. For each SKU, HMRC's guidance asks for details such as the GTIN barcode, brand, flavour and product type. It also asks for volume to the nearest 0.1ml, nicotine strength and a JPEG product image. Nicotine products also need their ECID or GBID notification number.

Most brand owners hold this information already. However, it often sits across spec sheets, artwork files and notification records. Pulling it into one clean dataset now avoids delays at the stamping stage.

Transitional stamps suit short runs, not long plans

A transitional stamp only helps if it goes on before 31 December 2026. So any stock that won't reach finishing by then should plan for digital from the start. Otherwise, you risk ordering stamps for a pipeline that outlasts the affixing window.

Digital stamping puts new work on whoever affixes

The digital stamp brings activation, data capture and scanning at several stages. Packed units also need aggregation codes for cartons, master cases and pallets. Operators report these through an API built to the GS1 EPCIS standard. None of this needs special hardware, since any iOS or Android device can scan a code through an app. Still, it needs a reliable process on every single run.

This matters most if an overseas factory stamps your goods. First, a UK representative must buy the stamps on the factory's behalf. Then the factory has to activate and scan every digital stamp correctly, outside the UK.

Your packaging still needs a home for the stamp

The stamp needs a clear spot on the outermost pack where it seals the opening. The supplier's testing shows a digital code still scans on curves down to a 10mm radius. So most boxes, bottles and pods can carry one. Even so, check your artwork before your next print run. For timing, our duty stamp timeline shows how far ahead stamp orders need to start.

How Xyfil covers your stamping, whichever route you take

Every brand reaches the UK market differently, so the stamp switch lands differently too. Below, we focus on what the move to digital stamps means on each route. For a full side-by-side of the services themselves, see our comparison of Xyfil's stamping and fulfilment routes.

If we already manufacture for you

Stamping already sits inside our production process. So the move from transitional to digital stamps happens on our line, and nothing changes on your side.

If you import part-finished stock

Your goods arrive without the retail box and stay unstamped until we finish them in the UK. As a result, you never hold transitional stamps that might outlast the affixing window. We simply apply the stamp each date requires, and from January that means digital. Our guide to importing part-finished stock covers the wider benefits of this route.

If you import retail-ready stock

We stamp your finished packs on arrival and release them to the market. From 1 January 2027, that stamp will be digital, and we handle activation and scanning as we affix it.

If your own overseas factory stamps

This route changes the most. Whoever affixes a digital stamp must activate and scan it, so your factory takes on that work. We plan the process with you before any stamps ship, alongside the bank guarantee and reconciliation the route requires.

If you're based overseas

You'll need a UK representative to take part in the scheme at all. Our import representation service covers registration, stamp requisition, duty accounting and HMRC liaison.

Once your stock is stamped

Our fulfilment and storage service holds stock in duty suspension until orders call for it. That way, your duty point follows your sales rather than your stock arrivals.

Vape duty stamp FAQs

When do transitional vape duty stamps stop?

The buying window closes on 30 November 2026. After that, the last day to apply one is 31 December 2026. New stock then takes digital stamps only.

Can stock with a transitional stamp still be sold in 2027?

HMRC's cut-offs apply to buying and affixing transitional stamps. Its guidance doesn't set a separate sell-by date for stock that already carries one. So if you plan to hold transitionally stamped stock for a long time, check your position with HMRC first.

Do overseas manufacturers need a UK representative?

Yes, if they want to affix stamps as part of their own manufacturing process. The UK representative applies for approval and buys the stamps on their behalf.

Does nicotine-free e-liquid need a duty stamp?

Yes. Vaping Products Duty covers all vaping liquid, with or without nicotine. So nicotine-free products need a stamp too.

Do I need special scanners for digital duty stamps?

No. HMRC's guidance sets no scanner model requirements, and an iOS or Android device can scan codes through an app. However, third-party scanners need their own integration with the supplier's API.

Preparing your brand for digital duty stamps

Transitional stamps will fade out within months, while digital stamps become the permanent standard. For most brand owners, the sensible move is to plan around digital now. Start with your product data, check your packaging, then pick the route that fits your supply chain.

Want a second pair of eyes? Send us your product list and current route to market. We'll show you how each stamp type affects your plans, and which Xyfil service keeps you covered. Book a call with the team.

One Week to Go: Why Vape Duty Stamps Run on Weeks, Not Days

Vaping Products Duty goes live on Thursday, 1st of October. By now, most brand owners know the headline numbers. Duty sits at 22p per ml. Every product released for UK sale also needs a vaping duty stamp on its retail pack.

What still catches people out is the lead time. A duty stamp is the last thing to go on the pack. Yet it’s one of the first things you need to plan. So if your first container arrives next week, the stamping work behind it should already be moving.

This guide walks back through the duty stamp timeline, step by step. Along the way, it shows where the weeks go and what you can still do if you’re starting late.

Why vaping duty stamps can’t wait for the goods to arrive

Every stamp links to a product record, an approved business and a secure delivery address. Only HMRC-approved purchasing operators can buy stamps. That means UK manufacturers, warehousekeepers and UK representatives. They order through the portal run by Cartor Security Printers, the supplier HMRC appointed for the scheme.

As a result, nobody stamps a container the week it lands. Four things have to line up first: a forecast, clean product data, a confirmed stamp order and a booked production slot. Miss one, and the goods sit in the warehouse.

The duty stamp timeline, working back from release

Picture your release date as the finish line, then count backwards. The week ranges below are planning guides rather than HMRC rules. However, the dependencies behind them are real.

Weeks before releaseStepWhat has to be true
6 to 8 weeksForecastVolumes by SKU agreed; purchase limit covers them
5 to 6 weeksProduct dataEvery SKU set up in the supplier system, all fields complete
Around 4 weeksStamp orderOrder confirmed, paid and scheduled for delivery
1 to 2 weeksBooked slotLine time booked for stamping, activation and aggregation

Step 1: Forecast (six to eight weeks out)

Start with volume by SKU. How many units of each product will you release, and when?

This matters for two reasons. First, HMRC sets stamp purchase limits over a rolling three-month period. It bases them on the information in the operator’s approval application. Operators can exceed that limit by up to 30%. They can also ask for a rise if they show a business need. Even so, a limit that doesn’t reflect your real volumes slows everything down.

Second, your forecast decides stamp format and order size. Stamps come as wet coils or dry stacks, with a minimum order of 1,000. A solid forecast lets your stamping partner order once instead of three times.

Step 2: Product data (five to six weeks out)

Next, every SKU needs a record in the supplier system before its stamps can go live. GOV.UK lists the fields HMRC expects. They include:

  • Product name and commercial description.
  • GTIN or EAN barcode.
  • Volume to the nearest 0.1ml.
  • Brand and flavour.
  • Product type: prefilled pod, prefilled device, bottle or other.
  • Nicotine content in mg/ml, plus the ECID or GBID where nicotine is above zero.
  • A JPEG image of the product.

Cartor states that none of these fields are optional. In practice, this step takes longer than most people expect. Barcodes go missing. Flavour names differ between the artwork and the spec sheet. Notification IDs sit with a different team. Each gap has to close before a single stamp goes on.

Step 3: Stamp order (around four weeks out)

With limits and SKUs in place, the approved operator can place the order. Cartor quotes a standard lead time of 15 days from order confirmation. After that, stamps travel by tracked, signed-for delivery, and only to HMRC-approved addresses.

Fifteen days sounds short. Add payment, delivery and a receipt check, though, and you’re close to three weeks. Then add any back-and-forth on SKU data. That’s why the stamp order belongs a month ahead of release.

Once the stamps arrive, they go into secure storage and a reconciliation log. HMRC expects routine checks on every stamp ordered, received, used, returned and destroyed.

Step 4: Booked slot (one to two weeks out)

Finally, the goods need line time. The slot covers stamp application, activation and aggregation. It also covers carton assembly, leaflets and sealing if the product arrives part-finished.

For digital stamps, activation happens at the point of affixing. Each activation records the time, place, operator and product. Aggregation codes then link each stamped unit to its carton, case and pallet using GS1 standards. At Xyfil, every run closes with a reconciliation pack, so the stamp count matches before anything leaves the building.

Slots fill up around deadlines. So book yours when you place the stamp order, rather than when the container is already on the water.

Starting late? What this means for the 1st of October

If you haven’t started yet, the maths is simple. You won’t clear forecast, data, order and slot on your own by Thursday.

You still have options, though, and the route now matters more than the date. Three of them help.

  • Hold stock in duty suspension. Goods in an approved excise warehouse haven’t been released for consumption, so the duty point hasn’t arrived. The amount of duty stays the same. Only the timing moves, which gives you room to finish the stamping workflow properly.
  • Import part-finished and finish in the UK. Components that arrive under duty suspension can be assembled, stamped and sealed here. The stamps stay in secure UK custody instead of travelling with the goods. You also keep onward duty-suspended movement, and duty falls due at release.
  • Work with a partner who already runs the workflow. An operator with portal access, SKU templates and planned line time turns a two-month job into a data and scheduling task.

We’ve manufactured in Preston since 2014. Over the past few months, we’ve built the stamp workflow into how we plan every production run. That way, forecast, data, order and slot move together instead of one after another.

Vaping Products Duty dates after the 1st of October still run on weeks

Go-live isn’t the last deadline, either. The same lead times apply to every date that follows.

  • 30 November 2026: the last day to buy transitional stamps.
  • 31 December 2026: the last day to affix transitional stamps.
  • 1 January 2027: only digital stamps may be affixed from this date.
  • 1 April 2027: every vaping product outside duty suspension must carry a stamp.

In other words, a brand that wants transitional stamps before the cut-off needs its forecast in hand by early October. Meanwhile, brands moving straight to digital need SKU data and scanning set up well before January.

Your next step

Wherever you are in the timeline, there’s a next step that fits.

  • Read: our guide to digital and transitional vaping duty stamps, if you’re still choosing a stamp type.
  • Check: your progress against our VPD readiness checklist to see which of the four steps you’ve covered.
  • Send: us your current route, covering who makes it, who ships it and who holds it. We’ll show you where the weeks go.
  • Talk: to the team on a 20-minute VPD readiness call. Get in touch with us here.

Which VPD Route Fits Your Business? Comparing Xyfil’s Stamping & Fulfilment Options

From October 1st, every unit of vaping liquid sold in the UK carries a duty stamp. That single rule reaches every brand owner in the market, no matter how your liquid gets made. Maybe Xyfil already manufactures your range. Maybe you import finished stock from an overseas factory. Maybe your production sits somewhere between the two. Either way, the question isn't whether you need a stamp on your product. It's which route gets you there without slowing your business down.

We built several service routes because brand owners don't all start from the same place. This article walks through each one. It looks closely at the stamping side, so you can work out which route fits your situation and book the readiness call that gets it moving.

Whichever way you make your liquid, the stamp still lands on you

Vaping Products Duty attaches to the product, not to whoever happens to manufacture it. So if you outsource production, import stock, or run your own overseas factory, the stamp requirement still follows your liquid to a UK shelf. Once you know a stamp has to go on, you need to know who puts it there, and how.

That's where the four routes below come in. Each one answers a different starting point. Together, they cover almost every brand owner working toward the 1st of October.

Already manufacturing with us? The stamp is already built in

If Xyfil makes your liquid, this part stays simple. Duty stamp affixing sits inside our standard production process, alongside batch tracking and the audit trail HMRC expects to see. You don't add a step, book a separate supplier, or plan a second movement of goods. The stamp goes on as your bottles come off the line, right alongside everything else we already do for you.

That's the advantage of one relationship covering the whole job. Nothing changes about how you work with us today. You simply end up with a stamped, compliant product, without lifting a finger.

Importing part-finished stock? UK Stamping & Finishing keeps you duty-suspended

Plenty of brand owners import in bulk and finish closer to the point of sale. The new duty hasn't broken that model. If anything, it's made the model stronger. Under UK Stamping & Finishing, your part-finished goods arrive at our Preston site under duty suspension. From there, we complete carton assembly and insert your leaflets. We apply the stamp, seal the packs, and case the finished product, all before anything moves on.

The reason this route works so well comes down to what it protects. Because your product travels in its labelled pouch, bottle or pod, without the retail box, stamps carry zero risk in transit. They're requisitioned, controlled and applied entirely within our approved premises instead. Because the goods stay duty-suspended throughout finishing, you also keep a further duty-suspended movement afterwards.

Duty falls due only when stock actually releases for sale, and you can stamp on demand rather than committing your whole shipment at the factory gate. Export the same batch instead, and you sidestep the penalty of destroying a stamp you never needed. We've written about this route in more depth elsewhere. It remains our strongest recommendation for any brand still deciding how to structure its supply chain before October.

Importing retail-ready stock? Duty Stamping Only gets it moving fast

Sometimes your goods arrive finished, packaged and ready for shelf, with nothing left to do but stamp them. That's Duty Stamping Only. We apply the stamp to your retail-ready product as it passes through our bonded warehouse. That happens on a single duty-suspended movement at import, and we release the goods into the UK market from there.

It's the simplest route on this list, and the trade-off is an honest one. Because the goods arrive already finished, you don't retain the onward bonded flexibility that part-finished stock gets under UK Stamping & Finishing. For a brand that already has its packaging locked down and just needs a compliant stamp applied, that trade-off rarely matters much. Speed usually wins out instead.

Manufacturing overseas at your own factory? Overseas Stamping under Bank Guarantee closes the gap

Not every brand owner wants to outsource their manufacturing and that's a perfectly reasonable position. If your own overseas factory already holds HMRC approval, we can still help. We act as your UK duty representative and dispatch your stamps to that approved address. We carry the legal and financial liability for every stamp from the moment it leaves our custody, with the strict reconciliation that arrangement demands handled as part of the service.

This route exists for one reason. A brand with an established overseas manufacturing relationship shouldn't have to unwind it just to get compliant. You keep your factory and your existing relationship. We handle the part of the process that has to happen on UK soil.

Once it's stamped, Fulfilment & Storage takes it from there

A stamped product still needs somewhere to sit and a way to reach your customer. Our fulfilment & Storage service covers goods-in and duty-suspended storage. It also covers pick, pack and dispatch to both retailers and consumers, with returns handled from the same site. Add it onto any of the four routes above, and your stamped stock never has to leave our facility until an order actually calls for it.

If you're based overseas yourself, Import Representation gets you started

Every route above assumes someone on UK soil is registered, accounting for duty, and talking to HMRC on your behalf. If that's not currently you, Import Representation is where you start. We act as your UK representative and handle scheme registration and stamp requisition. We also run the duty accounting and manage HMRC liaison, so an overseas manufacturer or brand owner gets a compliant route to market without setting up a UK operation from scratch.

On rates: compliance shouldn't carry a premium

A stamp applied properly, on a line built for the job, tends to cost less than one bolted onto a process that was never designed for it. That holds true across all four routes above. It's a large part of why brand owners come to us for stamping, even in cases where we haven't manufactured a drop of their liquid. Ask us about rates on a readiness call. We'll talk you through what each route costs against your actual volumes, rather than a generic price list.

The trust question, answered the same way every time

Whichever route you land on, the reconciliation behind it works to the same standard. Every stamp we apply gets tied back to an HMRC dataset and a GS1-aggregated batch record. That way, your stock stands up to an audit whenever HMRC asks to see it. That discipline runs through every route in this article, and it's the same discipline we've applied since 2014, through every rule change the industry has faced so far.

Which route fits you? A quick way to check

Run through these questions, and the right route usually becomes obvious fairly quickly:

  • Does Xyfil already manufacture your range? Your stamp is already handled.
  • Do your goods arrive part-finished? UK Stamping & Finishing is your route.
  • Do your goods arrive retail-ready? Duty Stamping Only gets you there.
  • Does your own overseas factory hold HMRC approval? Overseas Stamping under Bank Guarantee closes the gap.

Layer Fulfilment & Storage onto any of those answers. Add Import Representation underneath if you're based overseas yourself.

Book the call before the routes fill up

The 1st of October is now weeks away, and every brand owner working through this decision is racing the same date. Whichever route fits your business, the sooner you confirm it, the sooner your stock moves through the process instead of sitting behind it.

Book a VPD readiness call →

Import Part-Finished, Finish in the UK: The Smartest Route to Market Under VPD

If you manufacture or source e-liquid overseas, you're about to make a decision. Get it wrong, and it's expensive to unwind. Do you ship finished, stamped, retail-ready stock straight into the UK? Or do you import it part-finished and complete the job here?

Get it wrong, and you could burn your one shot at duty-suspended flexibility. That can happen before your stock has even cleared the port. Get it right, and you keep every option open, right up to the day you release stock for sale.

1 October 2026 is closing in fast. This isn't a decision you can afford to make on assumption. Here's the case for finishing in the UK, and why the timing matters more than most import brands realise.

Why the "finished at origin" route is riskier than it looks

It feels intuitive to finish everything overseas: fill it, cap it, stamp it, box it, ship it. One clean shipment, nothing left to do at this end. Under Vaping Products Duty, that instinct works against you.

Here's the mechanic that changes everything. Once your product is packaged as finished, retail-ready goods, HMRC allows just one further duty-suspended movement. Import a fully finished, already-stamped consignment, and that single move gets used up at the border. From that point on, any repositioning triggers the duty early. So does any onward transfer, or any change of plan. You've spent your flexibility before you've sold a single unit.

There's a second risk hiding in the same decision. Duty stamps are physical, serialised, and easy to damage in transit. Ship pre-stamped stock across borders and through freight handling, and you're exposing compliance-critical packaging to real risk. Knocks, moisture and rough handling are a normal part of long-haul shipping. Damage a stamp, and you've damaged a legal requirement, not just a label.

The smarter route: import part-finished, finish here

There's a better way to structure this. It's the route we build for import and overseas brands. You manufacture the base product overseas as usual. Instead of finishing and stamping it there, you ship it to us part-finished, under duty suspension. We complete the final stages here in the UK. That means carton assembly, leaflet insertion, duty stamping, sealing and casing, all inside an HMRC-approved facility.

Three things follow from that one change:

  • Your single duty-suspended movement stays available, not spent. The goods arrive part-finished, so they haven't triggered the one-move rule yet. That flexibility stays in your hands for whatever comes next. Export, onward transfer, or simply holding stock until you're ready to release it.
  • Duty stamping happens at the safest possible point, not the riskiest. Stamps get applied in a controlled UK facility, immediately before goods are released. Not months earlier, on the other side of a container ship.
  • Your duty point lands on release, not on arrival. VPD becomes due when finished, stamped stock actually leaves duty suspension for sale. That's a timing benefit, not a reduction in what you owe. You pay the same duty either way. You simply pay it when the goods actually reach the market, rather than the day they touch UK soil.

What this actually looks like day to day

This isn't a theoretical structure. It's a standing service, and it works like this. Your part-finished product arrives at our site under duty suspension, exactly as agreed with HMRC. We take it through final assembly and duty stamping, then sealing and casing to retail-ready standard. From there, it stays in our approved store until you tell us to release it. That release schedule can be a full run, or a rolling one matched to your actual sales.

For an overseas manufacturer or brand owner, that means something simple. You get a UK-based finishing and compliance partner without building UK excise infrastructure yourself. No separate UK entity to register. No excise warehouse application of your own. No new HMRC relationship to build from scratch under deadline pressure. You bring us the part-finished product. We bring the approvals, the facility, and the finishing capability.

Why the timing on this decision is urgent right now

Every week you wait is a week closer to 1 October with the decision still unmade. Three deadlines are converging on the same date, and none of them move for anyone:

  • VPD applies from 1 October 2026, at a flat £2.20 per 10ml. That covers every UK-sold vaping product, whatever the format or nicotine strength.
  • HMRC approval takes a minimum of 45 working days. That clock is already tight for anyone who hasn't started.
  • The duty stamp grace period runs only to 31 March 2027. Any finished, unstamped stock still in the supply chain after that date becomes a live compliance problem, not a future one.

If you're currently planning to ship finished stock and stamp at origin, this is the moment to stop and rework that plan. Don't wait until your next shipment is already at sea. Switching the structure of an import route takes coordination on both sides. That coordination only gets harder the closer you get to October.

The question to ask before your next shipment

Before you finalise your next order with an overseas manufacturer, ask one question. Will this shipment use up your one duty-suspended movement before it's even reached a UK customer? If the honest answer is yes, talk to us before that shipment leaves, not after.

We handle the UK side of this route for import brands and overseas manufacturers every day. Duty-suspended receipt, finishing, stamping, storage, and release timed to your actual sales. Want to talk through whether your current import route is spending flexibility you don't need to lose? Book a call or get in touch. We can also walk you through our current approvals and compliance credentials directly. Just ask.

Since 2014, Through Every Rule Change: Why Experience Matters More Under VPD

Every e-liquid manufacturer in the UK is telling brand owners the same thing right now: we're ready for VPD. It's the right message. We've said it before too, in 2016, in 2021, in 2025, and each time the rulebook changed, we proved it.

Vaping Products Duty (VPD) is simply the latest chapter. It isn't the first shift this industry has faced.

Rules and dates don't make for gripping reading on their own. But they answer the question every brand owner should ask a manufacturer right now: when the rules changed before, what did you actually do?

Every vape manufacturer says they're compliant. Fewer can say they've done it before.

Since 2014: built inside a changing rulebook, not before it

Xyfil has manufactured e-liquid, and later nicotine pouches, CBD and personal care products, from our Preston site since 2014. We didn't arrive once this industry had settled down. There was no settled version to arrive into. UK vape manufacturing has been rewritten, in some way, in almost every year we've operated.

Most manufacturers pick a moment when the rules are stable and build around that snapshot. Every later change then lands as a disruption. We never had that luxury. So we built compliance as an ongoing discipline, a job that never really finishes.

2016: TPD arrives, and we move early

The Tobacco Products Directive reshaped the industry almost overnight. Nicotine strength capped at 20mg/ml. Tank sizes capped at 2ml, bottle sizes at 10ml. Every product needed MHRA notification, ingredient disclosure and standardised health warnings before it could reach a shelf.

Plenty of manufacturers scrambled. We were among the first manufacturers in the UK to bring our production and notification process in line with TPD. We moved well ahead of brands who left it late and found themselves locked out of shelves while their paperwork caught up. Brands working with us kept trading. Others didn't.

Post-Brexit: same standard, new name

When the UK left the EU, TPD didn't vanish. It carried over into UK law as the Tobacco and Related Products Regulations, with MHRA notification continuing much as before. We'd already built our systems around meeting a strict notification standard. Updating the reference in the rulebook barely touched day-to-day production.

2025: the disposable ban, and a fast pivot

From 1 June 2025, the sale and supply of single-use disposable vapes became illegal across the UK. Brands built entirely around disposables faced a genuine scramble. New device formats, new manufacturing lines, new packaging, all against a hard deadline. We'd already built flexible, reusable-format production capacity well before the ban landed. Brands who came to us in that window switched to a partner with the capacity ready and waiting.

2026: Vaping Products Duty

Which brings us to now. VPD applies from 1 October 2026. Every UK-sold e-liquid and nicotine product carries a flat duty rate from that date, with duty stamps, HMRC registration and a formal approval process behind it. It's the most administratively demanding change this industry has faced.

We approached VPD the way we approached TPD and the disposable ban. Early, built as an operational project rather than a scramble against the calendar. We've spent the past year putting the compliance infrastructure in place that VPD requires. When 1 October arrives, it's a date we're positioned for.

Why this pattern should matter to you

A manufacturer's history with regulatory change tells you something a sales page can't: how they actually behave when the rules move. Some manufacturers wait and react. Others treat every new rule as an excuse to raise prices, or pass the risk downstream to the brands they supply.

Here's what a decade of doing this repeatedly should tell a brand owner weighing up a manufacturing partner:

  • The muscle is real, built over time. Meeting a regulatory deadline once could be luck, timing, or a good consultant. Meeting five of them, across a decade, under different governments and different rulebooks, is a pattern. A pattern is what you're actually buying when you choose a manufacturer.
  • Our compliance risk becomes your protection. Every rule change we've navigated happened on our side of the relationship. Your brand didn't have to carry it.
  • A long HMRC relationship counts for more when the rules tighten. Regulatory bodies deal with manufacturers they know. Ours has years of registrations, notifications and audits behind it, built long before VPD put pressure on the timeline.
  • Continuity is the real product. Brands that switched to us during the TPD transition, and again during the disposable ban, kept trading through both. Tenure like ours is supposed to buy you exactly that.

What this means for your brand under VPD

Right now, you're probably in one of three positions. Manufacturing in-house and racing the approval window. Unsure whether your current manufacturer is actually ready. Or importing, and wondering who handles the UK-side compliance for you.

Every one of those positions comes back to the same question. Has your manufacturer got a track record of getting through regulatory change cleanly? Or are you both about to find out together?

We'd rather you learned it from our history than from your own experience. Since 2014, we've done the same job through every version of this industry's rulebook: TPD, Brexit, the disposable ban, VPD. It's a pattern you can check, not a promise you have to take on faith.

If you want to talk through where your brand sits ahead of 1 October, book a readiness call by getting in touch. We can also walk you through our current approvals and compliance credentials directly.

What Xyfil’s Full VPD Approval Actually Means for the Brand Owners Who Work With Us

Xyfil's HMRC approval under the Vaping Products Duty scheme isn't new. We announced it, and by now most of our clients already know it. What's worth spelling out is what that approval actually covers. And what it means for a brand owner still choosing who to manufacture with.

That's because "approved" can mean a lot of things. A business can hold one licence and still leave a client exposed on the parts it doesn't cover. So before you compare manufacturers, it's worth understanding exactly what sits behind the word.

Five approvals, not one

Xyfil holds producer, importer, warehousekeeper, and duty stamp affixing approvals, together with UK duty representative status for overseas manufacturers. Each one covers a different point in your product's journey, and each one matters on its own.

Producer approval lets us manufacture vaping liquid under the VPD scheme. Importer approval covers goods brought in from overseas. Warehousekeeper approval lets us hold your stock in duty suspension. That way, the duty point lines up with your sales rather than your production schedule. Duty stamp affixing approval means we can apply the retail stamp ourselves, at our own premises. We don't need to send that job elsewhere. And UK duty representative status lets us act on behalf of overseas brand owners and manufacturers with no UK presence of their own.

Put together, those five approvals cover the full chain: production, import, storage, stamping, and representation. A brand owner working with a partner who holds only one or two of these still carries the gap themselves.

Why the stamp-affixing approval matters more than it sounds

Of the five, duty stamp affixing is easy to underrate. Every duty stamp carries real financial liability from the moment it's issued. HMRC penalties run to £11 per lost, stolen, or misused stamp. A single missing reel of a thousand stamps becomes an £11,000 exposure before any duty is even considered.

That liability sits with the UK duty representative, not the brand owner. So when we hold that approval and keep stamps in our own secure custody, the exposure stays with us. It stays inside a controlled, audited process, too. You don't need to manage stamp custody yourself. It was never designed to be split between two businesses in the first place.

Five ways this becomes useful to you

Holding the full set of approvals only matters if it turns into something a brand owner can actually use. In practice, it opens five distinct routes to market:

  • Import Representation, for overseas manufacturers and brand owners who need a UK presence to place products on the market compliantly.
  • UK Stamping & Finishing, for part-finished goods that arrive here and leave fully retail-ready.
  • Duty Stamping Only, for goods that already arrive finished and simply need the stamp applied.
  • Overseas Stamping under Bank Guarantee, for brands who need stamps applied at their own factory abroad.
  • Fulfilment & Storage, covering goods-in, duty-suspended storage, and pick, pack, and dispatch.

Each route suits a different starting point. The right one for you depends on how your product arrives, and how much of the process you want to hand over.

The route worth knowing about now

Of those five, one combination is worth flagging ahead of its own dedicated post next week. Bringing your product into the UK part-finished, rather than fully packaged, keeps your stock in duty suspension for longer. It also preserves an onward duty-suspended movement once we finish it here. That single detail changes how much flexibility you keep right up to the point of sale. We'll walk through exactly how and why in full next week.

What to check before you commit to any manufacturer

Whoever you work with, ask them plainly which of these five approvals they actually hold. Don't just ask whether they're "VPD approved." Ask where your duty stamps are held, and who carries the liability if one goes missing. Ask whether your stock can move under duty suspension more than once before it reaches you. The answers tell you how much of the compliance burden you're really handing over. They also show how much you're still quietly carrying yourself.

Ready to talk it through?

If you're weighing up manufacturing, importing, or white-label options before 1 October, it's worth having a direct conversation. Book a readiness call, and we'll walk through which route fits your product and your timeline.

Book a readiness call →

Your Bottle Is Now a Tax Document: Designing Packaging for Stamp Integrity

Your artwork used to answer to one boss: your brand. Since 1 October 2026, it answers to a second one too. That boss is HMRC. The Vaping Duty Stamps Scheme turns every bottle, pod and prefilled device into a compliance document. It's still your branding. But it's a tax record now too. Get the label wrong, and you can't legally sell what's inside it.

That sounds dramatic. The mechanics, though, are simple. So let's walk through three things. First, what a duty stamp actually is. Next, the dates that still matter. And finally, why your artwork needs attention now, before the new year rush.

What a duty stamp actually does

A vaping duty stamp isn't just an ink mark. It's a secure physical stamp with several security features. Right now, two versions exist. Transitional stamps carry physical security features only, and nobody scans them. Digital stamps, on the other hand, add a scannable code for authentication and supply chain tracing.

That code links each stamp to a set of product data. It records who affixed the stamp, along with where and when. It also covers the manufacturer, brand, flavour, volume and nicotine strength. Scans at key points then track the product's journey to the shelf.

Only HMRC-approved businesses can buy stamps. These are UK manufacturers, warehousekeepers and UK representatives, and they buy directly from the scheme's appointed supplier.

So the stamp does three jobs at once. It shows the product has gone through the duty system. On digital stamps, it gives HMRC a traceability trail. And it sits on your packaging, competing for space with your branding, your ingredients list, your batch code and everything else you already print.

There's one more rule that shapes your design. The stamp must go on the outermost retail packaging. It also has to seal that packaging, so nobody can open the pack without damaging it or the stamp.

The dates you're designing against

Vaping Products Duty went live on 1 October 2026, at a flat rate of £2.20 per 10ml. Duty stamps started on the same day. So any product you place into retail packaging for UK sale now needs a stamp, unless it moves under duty suspension.

From here, three dates shape your artwork plans:

  • November 30th, 2026: the last day to buy transitional stamps.
  • January 1st, 2027: from this date, you can only affix digital stamps.
  • April 1st, 2027: every vaping product outside duty suspension must carry a stamp, whenever someone made it. Until then, retailers can keep selling unstamped stock they already held.

Read those dates the way a production planner would. The switch to digital-only stamping on January 1st leaves very little room. Meanwhile, artwork revisions take longer than most brand owners expect. Print trials do too. And packaging sign-off is rarely quick, especially while your printer handles every other brand chasing the same date.

Why this is a packaging problem, not just a compliance one

Here's the part that catches brand owners out. A duty stamp needs its own reserved space on the pack. It shouldn't cover your logo, your nicotine warning or your batch code. Because the stamp also seals the pack, its position depends on how your packaging opens. On top of that, a digital stamp's code needs to stay scannable, so tight curves and awkward edges need checking early.

Treat it as a design brief, and you sidestep the expensive alternative. That alternative means reprinting an entire run because the stamp doesn't fit, hides required text or won't seal the pack. A short list of questions helps you get ahead of it.

Ask your manufacturer these questions

  • Has our pack got dedicated, unshared space for the stamp?
  • Does the stamp position seal the pack properly?
  • Will a digital stamp's code stay scannable on our bottle or carton shape?
  • Does the stamp interfere with any of our mandatory text?
  • Is our artwork ready for digital-only stamping from 1 January?
  • Who buys and holds our stamps, and how does that fit our supply chain?
  • Will stamp integrity survive our real production line, not just a design mock-up?

If your manufacturer can't answer these clearly today, your artwork risks becoming a rush job. And that tends to happen just as every other brand starts chasing the same print slots.

Build it into your next artwork pass

The brands handling this well aren't racing the deadline. Instead, they fold stamp space into whatever artwork revision they've already planned. That way, compliance rides alongside routine design work. It never turns into an emergency reprint.

It's a small ask right now. Left until the new year, though, it becomes a scramble. You'd compete against every other brand's print run, your own retail deadlines and a shrinking supply of press time.

Talk to us before your next print run

We work through label layout as part of production planning, and we can take on your packaging artwork too. As a result, stamp space, mandatory text and your brand all sit together on the same artwork, first time. Want a second pair of eyes on your packaging before your next print run? Request a packaging audit, and we'll walk through it with you.

Request a packaging audit →

British-Made vs Imported: What VPD Means for Cross-Border Brands

If your e-liquid comes from overseas, the 1st of October 2026 changes the maths. Vaping Products Duty applies to your stock the moment it enters the country, unless that stock goes straight into duty suspension. So the real question for any cross-border brand isn't just “how much will VPD cost me?” It's this: does importing still make sense once VPD, customs, and duty stamps all stack up together?

This article walks through what actually changes for imported liquid, and also where UK-made production sidesteps some of that complexity entirely.

What changes for imported e-liquid on 1 October

Right now, many brands treat import as a simple supply chain step. Order stock, clear customs, sell it on. From 1 October, that changes in three concrete ways.

First, you account for VPD at the point of import, unless the goods move directly into an approved excise or customs warehouse under duty suspension. If they don't, the duty falls due there and then. It doesn't wait until you sell the stock.

Second, duty stamps have to be on the product before it's released for UK consumption. If your overseas manufacturer applies the stamps before shipping, someone in the UK still has to manage that process. That someone is a UK representative, approved by HMRC specifically to purchase and handle stamps on behalf of an overseas manufacturer.

Third, your customs declaration now carries excise weight, not just trade weight. You need the correct tariff code and an accurate net liquid volume. You also need the paperwork behind it — invoices, packing lists, bills of lading. Get any of that wrong, and you risk delays or a seizure, not just a queried invoice.

The UK representative problem, in plain English

Here's the part that catches most import-led brands off guard. If your manufacturer sits overseas, they can't simply apply for UK duty stamps themselves. HMRC requires a UK-based entity to act as their representative instead. That entity needs its own approval, and it manages the stamps on the manufacturer's behalf.

That leaves a cross-border brand with a real choice before October. Find, and vet, a UK representative your overseas manufacturer trusts. Or find a UK partner who removes the question entirely by manufacturing here in the first place.

Either way, someone in your supply chain has to own this. It can't sit with nobody.

Stacking the real cost of importing after VPD

Before VPD, an overseas manufacturing route usually looked cheaper on paper. After 1 October, that comparison gets more complicated. The cost of imported liquid now includes several layers stacked on top of each other:

  • The landed cost of the product itself — manufacturing, freight, and any existing import duty or tariff
  • VPD at £0.20 per ml (that's £2.20 for a 10ml), due at import unless you've arranged duty suspension
  • The UK representative arrangement, if your stamps get applied overseas
  • Customs brokerage, plus the extra declaration detail excise treatment now demands
  • The operational risk of a shipment held up, or stock seized, over a stamp or paperwork error

None of this makes importing impossible. But the gap between a cheap overseas quote and landed, compliant, sellable UK stock gets wider. It's worth measuring properly, rather than assuming the old numbers still hold.

Manufacturing in the UK removes several of those layers at once. There's no import accounting step and no separate UK representative to arrange. There's also no cross-border shipment sitting at risk of a stamp error before it even reaches your warehouse.

The risk you inherit, not just the cost

Cost is only half the picture. When you buy finished liquid from overseas, you're also trusting someone else's compliance. That's someone you can't easily audit, and who may not fully understand UK excise law.

If stamps are missing, wrong, or applied by an unapproved party, HMRC can seize the stock. That's not a fine you negotiate afterwards. It's stock that simply doesn't reach your customers. And because the duty stamp scheme is new for everyone, an overseas manufacturer's confidence isn't the same thing as their compliance.

Questions worth asking before you commit

If you're weighing up whether to keep importing, put these questions to any current or prospective overseas supplier:

  • Who is your approved UK representative for duty stamps, and have you verified their HMRC approval yourself?
  • Will the stamps be applied before the stock leaves origin, or once it reaches the UK?
  • What documentation will you receive to prove duty has been correctly accounted for?
  • What happens, contractually, if a shipment gets held or seized over a stamping or paperwork issue?

If those answers feel vague, treat that as the signal to act.

Why brands are moving production onshore

None of this is about avoiding VPD. The duty applies to UK-made and imported liquid alike, and the rate doesn't change based on where you manufacture. What changes is how much complexity sits between production and a compliant sale.

Manufacturing in the UK collapses that chain. There's one legal entity responsible for the product and one compliance relationship to manage. There's no cross-border handoff where responsibility can blur. For a brand that's spent the last few months untangling UK representative rules and import declarations, that simplicity is the real appeal.

Xyfil's HMRC approval for Vaping Products Duty has been granted, and this covers importing as well as manufacturing within the UK. For more on our Vaping Products Duty services, read more here.