• 01772 888 778
  • info@xyfil.com
  • Unit 1 & 2, Durton Lane Business Park, Preston, PR3 5LR

Category Archives: Production

Digital Duty Stamps: What to Ask Your Manufacturer Before January 1st

From January 1st, 2027, only digital duty stamps can go on vaping products in the UK. Transitional stamps had a short life by design, and their window is now closing. For brand owners, that makes the next few weeks a useful checkpoint. If your manufacturer applies your stamps, the switch happens on their line and under their approvals. So it's worth asking a few clear questions now, while there's plenty of time to act on the answers.

This guide gives you seven of them. Each one comes with a note on what a good answer sounds like. You can use them with your current manufacturer, or with any partner you're considering.

Key takeaways

  • From January 1st, 2027, only digital duty stamps can be affixed. You can buy transitional stamps until November 30th and affix them until December 31st, 2026, according to HMRC's key dates.
  • Whoever applies a digital stamp must activate it at that moment. After that, operators scan it at set points.
  • Your manufacturer's approvals, data handling and stamp controls now shape how smoothly your stock reaches the shelf.
  • Seven simple questions show whether your set-up is ready for the switch.

Why the switch to digital duty stamps is a good moment to check in

Since Vaping Products Duty went live on October 1st, every new duty-liable product released for UK sale has needed a stamp. Until now, many brands have used transitional stamps. These carry physical security features only, so nobody scans them.

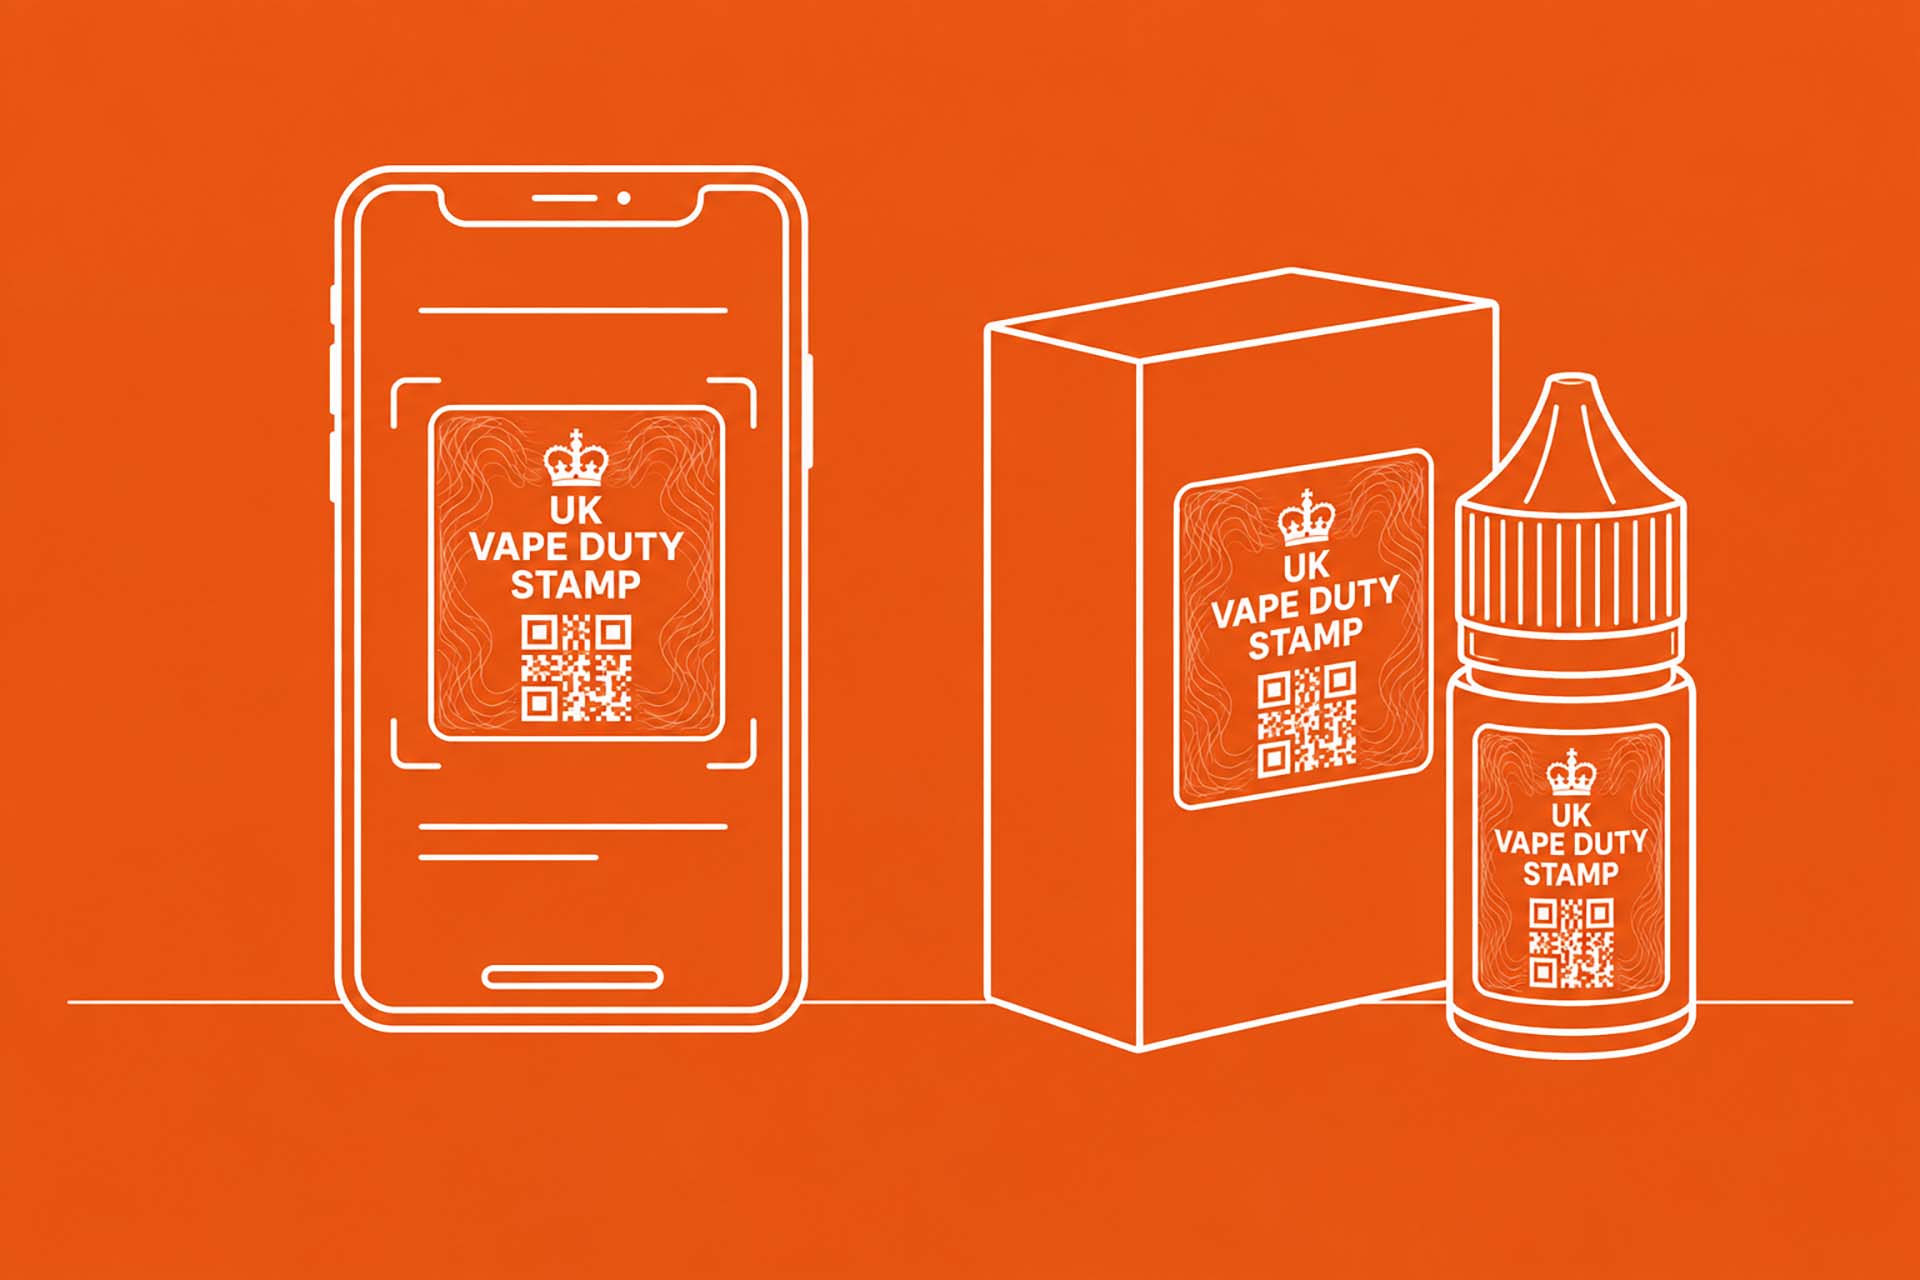
Digital stamps add a scannable code. Whoever applies the stamp must activate it at the point of affixing and record data about the product. After that, operators scan it again at set points, including release for consumption, as HMRC's stamp guidance sets out.

In short, more of the work now sits with whoever affixes your stamps. That's good news if you have a well-prepared partner, because the extra steps happen out of sight. It also means a quick conversation now can save a scramble in January. Our guide to digital vs transitional vape duty stamps covers the mechanics in full. Here, we focus on the questions.
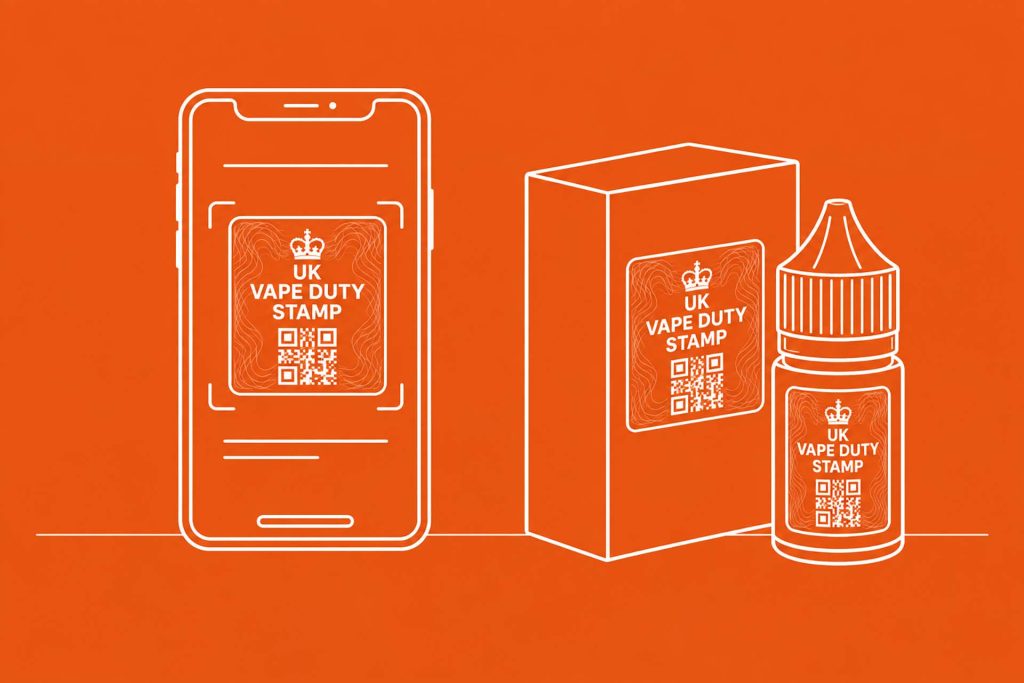
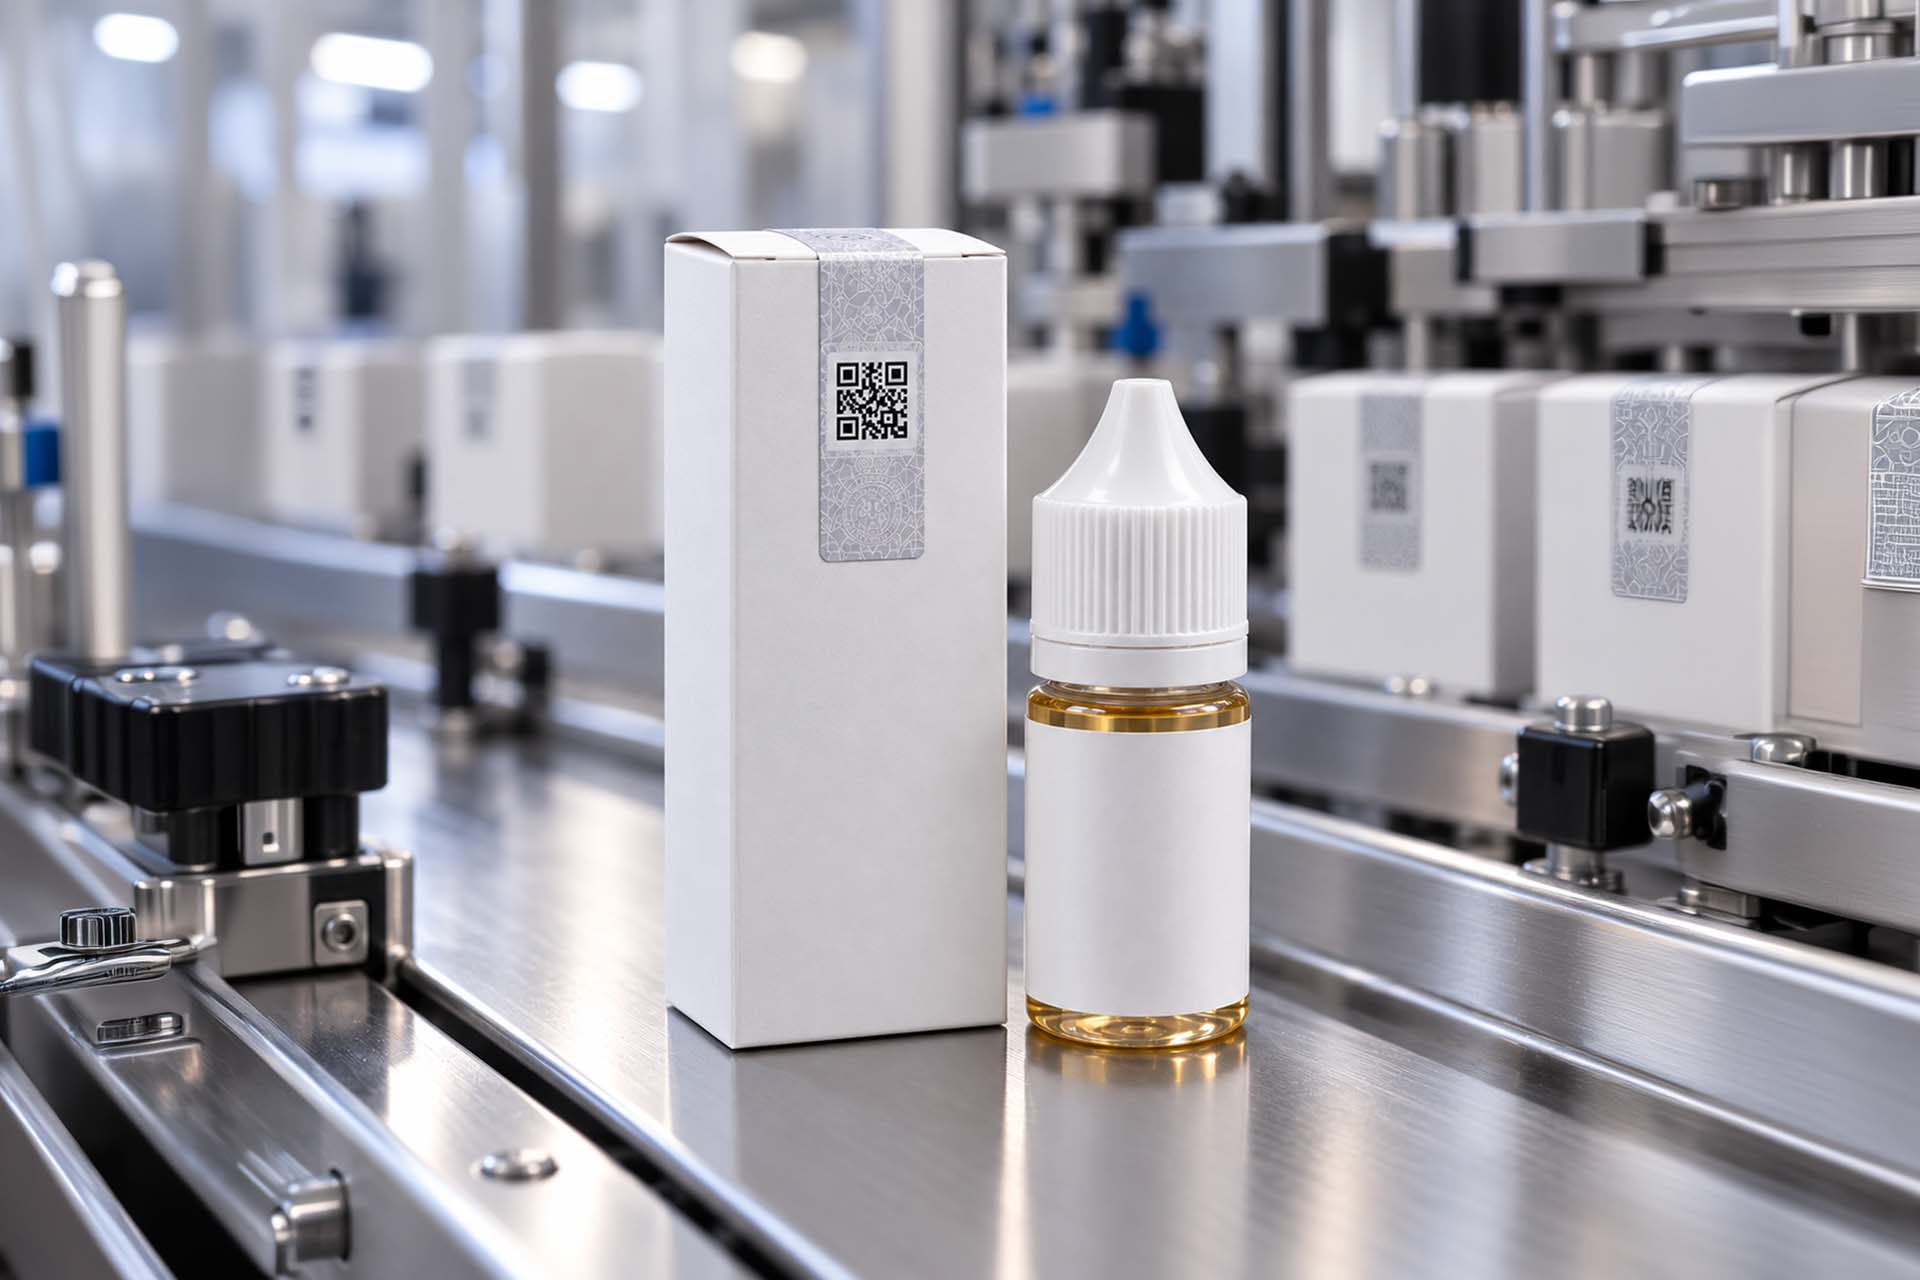
Digital vape stamp on E-liquid products

Seven questions to ask your manufacturer about digital duty stamps

1. Which approvals do you hold, and which ones cover stamping?

Only HMRC-approved purchasing operators can buy duty stamps. That means UK manufacturers, warehousekeepers and UK representatives. They order through the appointed supplier's secure platform.

So start with the basics. Ask which approvals your manufacturer holds, and whether they include stamp affixing at their own site.

A good answer: a clear list of approvals, plus a plain explanation of who buys, holds and applies your stamps.

2. Are you already applying digital stamps?

Digital stamps have been on sale since September 1st, 2026. Some operators started with them straight away, while others used transitional stamps first. Either approach works until December 31st.

From January 1st, however, every stamp needs activating as it goes on. Each activation records details such as the time, date and address of affixing, the operator and the product. Ask whether your manufacturer has already run digital stamps through its line, or when it plans to start.

A good answer: a firm start date, and a trial run before your first January batch.

3. How will you set up my product data?

Every SKU needs a record in the stamp supplier's system before its stamps can go live. HMRC's guidance lists ten fields. They include the GTIN barcode, volume to the nearest 0.1ml, brand, flavour, product type and nicotine content. Nicotine products also need their ECID or GBID.

Ask who builds these records, and what they need from you. When a brand moves its production to us, product data is one of the first things we look at. Every stamp depends on it, so getting it right early keeps the first run on schedule.

A good answer: a simple template, one point of contact and a check before the first run.

4. Who generates aggregation codes, and how do you record sales?

Digital stamps link to higher-level packaging through aggregation codes. These connect each stamped unit to its carton, master case and pallet. Either the manufacturer or the importer can generate them. Operators then report each link through an API built on the GS1 EPCIS standard.

There's a useful shortcut here too. At the final exit-to-market scan, an operator can declare a sale event for an aggregate code. That status then applies to every code linked beneath it, so nobody needs to scan each unit one by one.

A good answer: a named owner for aggregation, and a process that records cases and pallets rather than single units wherever it can.

5. Where do you hold my stamps, and how do you reconcile them?

HMRC expects operators to keep stamps in secure storage with access controls. It also expects routine reconciliations of stamps ordered, received, used, returned and destroyed. On top of that, operators need incident processes for loss, theft, damage and discrepancies.

Digital stamps add one more date to track. Operators must activate stamps within 12 months of receiving them, or a penalty may apply.

A good answer: stamps held securely in the UK, a reconciliation after every run, and records you can see on request.

6. What happens to any transitional stamps left after December 31st?

Transitional stamps can't go on after December 31st, 2026. So it's worth asking whether your manufacturer expects any to be left over, and what it plans to do with them.

Destroying unused stamps also follows a set process. Operators must tell HMRC the method, time, date and location before they destroy any stamps.

A good answer: an ordering plan that keeps leftovers low, and a clear process for any that remain.

7. Does your stamp purchase limit cover my volumes?

HMRC sets each operator a purchase limit over a rolling three-month period. Operators may go over it by up to 30%. They can also ask for a rise if they show a business need.

So if you plan to grow, launch new flavours or move more production across, share your forecast early. Our duty stamp timeline shows how far ahead each step needs to start.

A good answer: confirmation that your volumes fit, plus a plan for busy months.
Industrial printing machine printing labels in batches

What good answers have in common

Look back over the answers, and a pattern usually appears. Strong partners answer quickly and specifically. They name who does each step. They show you records instead of describing them. And they treat your forecast and product data as shared work, with clear deadlines on both sides.

If a few answers feel vague, that's fine. It simply shows you where to ask a follow-up question before January. For a wider view of the partnership, see our five signs your manufacturer may be holding your brand back.

How Xyfil answers these questions

We've manufactured e-liquid in Preston since 2014. Our VPD approvals cover production, import, warehousing, duty stamp affixing and UK duty representation. As a result, buying, holding and applying your stamps all happen within one approved business.

We apply both transitional and digital duty stamps today, so you can move to digital whenever it suits your range before January 1st. We've built the stamp workflow into how we plan every production run. Your stamps stay in our secure UK custody, and every run closes with a reconciliation pack. Each stamp then ties back to its HMRC dataset and a GS1-aggregated batch record.

We can also take on your packaging artwork, so the stamp has a clear home on your pack from the first print. For artwork questions, our guide to designing packaging for stamp integrity is a good next read. And if you import, our comparison of stamping and fulfilment routes shows how each route handles the move to digital.

Digital duty stamp FAQs

When do digital duty stamps become mandatory?

From January 1st, 2027, only digital duty stamps can be affixed to vaping products in the UK. Approved businesses can buy transitional stamps until November 30th, 2026 and affix them until December 31st, 2026. Digital stamps have been on sale since September 1st, 2026, so operators can switch sooner.

Do I need my own HMRC approval to use digital duty stamps?

Not if a partner applies them for you. Only HMRC-approved manufacturers, warehousekeepers and UK representatives can buy duty stamps. If your manufacturer holds stamp approvals, it buys, activates and applies the stamps on your behalf. You'll still need to supply accurate product data for each SKU.

What data does a digital duty stamp need?

Each SKU needs a record with ten fields. These include the product name, description, GTIN barcode, volume to the nearest 0.1ml, brand, flavour and product type. The record also covers nicotine content and a JPEG image. Products containing nicotine need their ECID or GBID notification number too.

Can retailers scan digital duty stamps yet?

HMRC says retailers and consumers will be able to scan digital stamps to check authenticity in due course. For now, approved operators scan them at affixing, during permitted duty-suspended movements and at release for consumption. Codes work with standard scanners, and phones can read them through an app.

Get your range ready for digital duty stamps

The move to digital stamps is a chance to tidy your product data and confirm your stamping set-up, well ahead of the new year. Send us your SKU list and a short note on how your range is made and stamped today. We'll show you how it moves onto digital stamps, and what we'd need from you to get started.'ll show you how it moves onto digital stamps, and what we'd need from you to get started.
Get in touch with the team.

Digital vs Transitional Vape Duty Stamps: What Brand Owners Need to Know

Vaping Products Duty (VPD) applies from 1 October 2026. From then, every vaping product made in or imported into the UK needs a vaping duty stamp before sale. However, the scheme starts with two different stamps, and they follow very different timelines. For brand owners, that difference shapes packaging, stock planning and even your route to market. So here's a clear guide to both stamp types, what each one means for your brand, and how to keep your stamping covered.

What a vape duty stamp does

Vaping Products Duty adds £2.20 of excise duty for every 10ml of vaping liquid. The duty stamp works alongside it as visible proof. It's a secure label with physical security features, and it helps retailers, enforcement teams and HMRC spot legitimate stock.

The stamp goes on the outermost retail packaging. That means the box, or the bottle itself if you sell it without a box. It also has to seal the pack, so nobody can open it without damaging the packaging or the stamp. Stamps can't be reused, either.

Across the trade, people often call this "vape stamp duty". Officially, the rules sit under HMRC's Vaping Duty Stamps Scheme (VDS). They cover every e-liquid, whether it contains nicotine or not.

Transitional vs digital duty stamps: the core difference

Both stamps do the same basic job. The real difference shows up after the stamp goes on.

The transitional duty stamp

The transitional stamp carries physical security features only. It has no scannable code, so nobody scans it at any point in the supply chain. HMRC introduced it as a bridge, giving production lines time to adapt before the digital system takes over.

The digital duty stamp

The digital stamp carries the same physical features, plus a unique scannable code. Whoever applies it must activate it at the moment of affixing. That activation links each stamp to a set of product and operator details. After that, the stamp gets scanned again at set points, including permitted movements under duty suspension and release for consumption.

In practice, the digital stamp turns every retail unit into a traceable record. As a result, HMRC can follow a product from the production line to the shelf.

FeatureTransitional stampDigital stamp
Physical security featuresYesYes
Scannable unique codeNoYes
Activation when affixedNoYes, by the affixing operator
Scanned through the supply chainNoYes, at affixing, permitted duty-suspended movements and release
Linked product dataNoYes, from the SKU record
Aggregation codes for cartons and palletsNoYes
Long-term roleBeing phased outThe permanent standard

Transitional stamp deadlines and the dates to plan around

The transitional stamp has a short, fixed life. Approved businesses can buy transitional stamps until 30 November 2026 and affix them until 31 December 2026. Digital stamps have been available since 1 September 2026. Then, from 1 January 2027, digital becomes the only stamp anyone can affix.

Meanwhile, a separate clock runs for older stock. Retailers and wholesalers can keep selling eligible unstamped stock they already hold until 31 March 2027. After that, every vaping product outside duty suspension needs a stamp.

You may still see older dates online. HMRC's first timetable closed transitional stamp sales on 31 August 2026. It then extended the window following industry feedback, so the dates above are the current ones.

What brand owners need to know

You probably won't buy stamps yourself

Only HMRC-approved purchasing operators can buy stamps. That means UK manufacturers, warehousekeepers and UK representatives, ordering through the appointed supplier's secure platform. HMRC also caps each operator's purchases over a rolling three-month period. So unless you hold those approvals yourself, your stamps come through a partner. For that reason, your partner's approvals, limits and stamp controls matter as much as your own planning.

Your product data becomes part of the stamp

Digital stamps link to product records in the supplier's system. For each SKU, HMRC's guidance asks for details such as the GTIN barcode, brand, flavour and product type. It also asks for volume to the nearest 0.1ml, nicotine strength and a JPEG product image. Nicotine products also need their ECID or GBID notification number.

Most brand owners hold this information already. However, it often sits across spec sheets, artwork files and notification records. Pulling it into one clean dataset now avoids delays at the stamping stage.

Transitional stamps suit short runs, not long plans

A transitional stamp only helps if it goes on before 31 December 2026. So any stock that won't reach finishing by then should plan for digital from the start. Otherwise, you risk ordering stamps for a pipeline that outlasts the affixing window.

Digital stamping puts new work on whoever affixes

The digital stamp brings activation, data capture and scanning at several stages. Packed units also need aggregation codes for cartons, master cases and pallets. Operators report these through an API built to the GS1 EPCIS standard. None of this needs special hardware, since any iOS or Android device can scan a code through an app. Still, it needs a reliable process on every single run.

This matters most if an overseas factory stamps your goods. First, a UK representative must buy the stamps on the factory's behalf. Then the factory has to activate and scan every digital stamp correctly, outside the UK.

Your packaging still needs a home for the stamp

The stamp needs a clear spot on the outermost pack where it seals the opening. The supplier's testing shows a digital code still scans on curves down to a 10mm radius. So most boxes, bottles and pods can carry one. Even so, check your artwork before your next print run. For timing, our duty stamp timeline shows how far ahead stamp orders need to start.

How Xyfil covers your stamping, whichever route you take

Every brand reaches the UK market differently, so the stamp switch lands differently too. Below, we focus on what the move to digital stamps means on each route. For a full side-by-side of the services themselves, see our comparison of Xyfil's stamping and fulfilment routes.

If we already manufacture for you

Stamping already sits inside our production process. So the move from transitional to digital stamps happens on our line, and nothing changes on your side.

If you import part-finished stock

Your goods arrive without the retail box and stay unstamped until we finish them in the UK. As a result, you never hold transitional stamps that might outlast the affixing window. We simply apply the stamp each date requires, and from January that means digital. Our guide to importing part-finished stock covers the wider benefits of this route.

If you import retail-ready stock

We stamp your finished packs on arrival and release them to the market. From 1 January 2027, that stamp will be digital, and we handle activation and scanning as we affix it.

If your own overseas factory stamps

This route changes the most. Whoever affixes a digital stamp must activate and scan it, so your factory takes on that work. We plan the process with you before any stamps ship, alongside the bank guarantee and reconciliation the route requires.

If you're based overseas

You'll need a UK representative to take part in the scheme at all. Our import representation service covers registration, stamp requisition, duty accounting and HMRC liaison.

Once your stock is stamped

Our fulfilment and storage service holds stock in duty suspension until orders call for it. That way, your duty point follows your sales rather than your stock arrivals.

Vape duty stamp FAQs

When do transitional vape duty stamps stop?

The buying window closes on 30 November 2026. After that, the last day to apply one is 31 December 2026. New stock then takes digital stamps only.

Can stock with a transitional stamp still be sold in 2027?

HMRC's cut-offs apply to buying and affixing transitional stamps. Its guidance doesn't set a separate sell-by date for stock that already carries one. So if you plan to hold transitionally stamped stock for a long time, check your position with HMRC first.

Do overseas manufacturers need a UK representative?

Yes, if they want to affix stamps as part of their own manufacturing process. The UK representative applies for approval and buys the stamps on their behalf.

Does nicotine-free e-liquid need a duty stamp?

Yes. Vaping Products Duty covers all vaping liquid, with or without nicotine. So nicotine-free products need a stamp too.

Do I need special scanners for digital duty stamps?

No. HMRC's guidance sets no scanner model requirements, and an iOS or Android device can scan codes through an app. However, third-party scanners need their own integration with the supplier's API.

Preparing your brand for digital duty stamps

Transitional stamps will fade out within months, while digital stamps become the permanent standard. For most brand owners, the sensible move is to plan around digital now. Start with your product data, check your packaging, then pick the route that fits your supply chain.

Want a second pair of eyes? Send us your product list and current route to market. We'll show you how each stamp type affects your plans, and which Xyfil service keeps you covered. Book a call with the team.

One Week to Go: Why Vape Duty Stamps Run on Weeks, Not Days

Vaping Products Duty goes live on Thursday, 1st of October. By now, most brand owners know the headline numbers. Duty sits at 22p per ml. Every product released for UK sale also needs a vaping duty stamp on its retail pack.

What still catches people out is the lead time. A duty stamp is the last thing to go on the pack. Yet it’s one of the first things you need to plan. So if your first container arrives next week, the stamping work behind it should already be moving.

This guide walks back through the duty stamp timeline, step by step. Along the way, it shows where the weeks go and what you can still do if you’re starting late.

Why vaping duty stamps can’t wait for the goods to arrive

Every stamp links to a product record, an approved business and a secure delivery address. Only HMRC-approved purchasing operators can buy stamps. That means UK manufacturers, warehousekeepers and UK representatives. They order through the portal run by Cartor Security Printers, the supplier HMRC appointed for the scheme.

As a result, nobody stamps a container the week it lands. Four things have to line up first: a forecast, clean product data, a confirmed stamp order and a booked production slot. Miss one, and the goods sit in the warehouse.

The duty stamp timeline, working back from release

Picture your release date as the finish line, then count backwards. The week ranges below are planning guides rather than HMRC rules. However, the dependencies behind them are real.

Weeks before releaseStepWhat has to be true
6 to 8 weeksForecastVolumes by SKU agreed; purchase limit covers them
5 to 6 weeksProduct dataEvery SKU set up in the supplier system, all fields complete
Around 4 weeksStamp orderOrder confirmed, paid and scheduled for delivery
1 to 2 weeksBooked slotLine time booked for stamping, activation and aggregation

Step 1: Forecast (six to eight weeks out)

Start with volume by SKU. How many units of each product will you release, and when?

This matters for two reasons. First, HMRC sets stamp purchase limits over a rolling three-month period. It bases them on the information in the operator’s approval application. Operators can exceed that limit by up to 30%. They can also ask for a rise if they show a business need. Even so, a limit that doesn’t reflect your real volumes slows everything down.

Second, your forecast decides stamp format and order size. Stamps come as wet coils or dry stacks, with a minimum order of 1,000. A solid forecast lets your stamping partner order once instead of three times.

Step 2: Product data (five to six weeks out)

Next, every SKU needs a record in the supplier system before its stamps can go live. GOV.UK lists the fields HMRC expects. They include:

  • Product name and commercial description.
  • GTIN or EAN barcode.
  • Volume to the nearest 0.1ml.
  • Brand and flavour.
  • Product type: prefilled pod, prefilled device, bottle or other.
  • Nicotine content in mg/ml, plus the ECID or GBID where nicotine is above zero.
  • A JPEG image of the product.

Cartor states that none of these fields are optional. In practice, this step takes longer than most people expect. Barcodes go missing. Flavour names differ between the artwork and the spec sheet. Notification IDs sit with a different team. Each gap has to close before a single stamp goes on.

Step 3: Stamp order (around four weeks out)

With limits and SKUs in place, the approved operator can place the order. Cartor quotes a standard lead time of 15 days from order confirmation. After that, stamps travel by tracked, signed-for delivery, and only to HMRC-approved addresses.

Fifteen days sounds short. Add payment, delivery and a receipt check, though, and you’re close to three weeks. Then add any back-and-forth on SKU data. That’s why the stamp order belongs a month ahead of release.

Once the stamps arrive, they go into secure storage and a reconciliation log. HMRC expects routine checks on every stamp ordered, received, used, returned and destroyed.

Step 4: Booked slot (one to two weeks out)

Finally, the goods need line time. The slot covers stamp application, activation and aggregation. It also covers carton assembly, leaflets and sealing if the product arrives part-finished.

For digital stamps, activation happens at the point of affixing. Each activation records the time, place, operator and product. Aggregation codes then link each stamped unit to its carton, case and pallet using GS1 standards. At Xyfil, every run closes with a reconciliation pack, so the stamp count matches before anything leaves the building.

Slots fill up around deadlines. So book yours when you place the stamp order, rather than when the container is already on the water.

Starting late? What this means for the 1st of October

If you haven’t started yet, the maths is simple. You won’t clear forecast, data, order and slot on your own by Thursday.

You still have options, though, and the route now matters more than the date. Three of them help.

  • Hold stock in duty suspension. Goods in an approved excise warehouse haven’t been released for consumption, so the duty point hasn’t arrived. The amount of duty stays the same. Only the timing moves, which gives you room to finish the stamping workflow properly.
  • Import part-finished and finish in the UK. Components that arrive under duty suspension can be assembled, stamped and sealed here. The stamps stay in secure UK custody instead of travelling with the goods. You also keep onward duty-suspended movement, and duty falls due at release.
  • Work with a partner who already runs the workflow. An operator with portal access, SKU templates and planned line time turns a two-month job into a data and scheduling task.

We’ve manufactured in Preston since 2014. Over the past few months, we’ve built the stamp workflow into how we plan every production run. That way, forecast, data, order and slot move together instead of one after another.

Vaping Products Duty dates after the 1st of October still run on weeks

Go-live isn’t the last deadline, either. The same lead times apply to every date that follows.

  • 30 November 2026: the last day to buy transitional stamps.
  • 31 December 2026: the last day to affix transitional stamps.
  • 1 January 2027: only digital stamps may be affixed from this date.
  • 1 April 2027: every vaping product outside duty suspension must carry a stamp.

In other words, a brand that wants transitional stamps before the cut-off needs its forecast in hand by early October. Meanwhile, brands moving straight to digital need SKU data and scanning set up well before January.

Your next step

Wherever you are in the timeline, there’s a next step that fits.

  • Read: our guide to digital and transitional vaping duty stamps, if you’re still choosing a stamp type.
  • Check: your progress against our VPD readiness checklist to see which of the four steps you’ve covered.
  • Send: us your current route, covering who makes it, who ships it and who holds it. We’ll show you where the weeks go.
  • Talk: to the team on a 20-minute VPD readiness call. Get in touch with us here.

Which VPD Route Fits Your Business? Comparing Xyfil’s Stamping & Fulfilment Options

From October 1st, every unit of vaping liquid sold in the UK carries a duty stamp. That single rule reaches every brand owner in the market, no matter how your liquid gets made. Maybe Xyfil already manufactures your range. Maybe you import finished stock from an overseas factory. Maybe your production sits somewhere between the two. Either way, the question isn't whether you need a stamp on your product. It's which route gets you there without slowing your business down.

We built several service routes because brand owners don't all start from the same place. This article walks through each one. It looks closely at the stamping side, so you can work out which route fits your situation and book the readiness call that gets it moving.

Whichever way you make your liquid, the stamp still lands on you

Vaping Products Duty attaches to the product, not to whoever happens to manufacture it. So if you outsource production, import stock, or run your own overseas factory, the stamp requirement still follows your liquid to a UK shelf. Once you know a stamp has to go on, you need to know who puts it there, and how.

That's where the four routes below come in. Each one answers a different starting point. Together, they cover almost every brand owner working toward the 1st of October.

Already manufacturing with us? The stamp is already built in

If Xyfil makes your liquid, this part stays simple. Duty stamp affixing sits inside our standard production process, alongside batch tracking and the audit trail HMRC expects to see. You don't add a step, book a separate supplier, or plan a second movement of goods. The stamp goes on as your bottles come off the line, right alongside everything else we already do for you.

That's the advantage of one relationship covering the whole job. Nothing changes about how you work with us today. You simply end up with a stamped, compliant product, without lifting a finger.

Importing part-finished stock? UK Stamping & Finishing keeps you duty-suspended

Plenty of brand owners import in bulk and finish closer to the point of sale. The new duty hasn't broken that model. If anything, it's made the model stronger. Under UK Stamping & Finishing, your part-finished goods arrive at our Preston site under duty suspension. From there, we complete carton assembly and insert your leaflets. We apply the stamp, seal the packs, and case the finished product, all before anything moves on.

The reason this route works so well comes down to what it protects. Because your product travels in its labelled pouch, bottle or pod, without the retail box, stamps carry zero risk in transit. They're requisitioned, controlled and applied entirely within our approved premises instead. Because the goods stay duty-suspended throughout finishing, you also keep a further duty-suspended movement afterwards.

Duty falls due only when stock actually releases for sale, and you can stamp on demand rather than committing your whole shipment at the factory gate. Export the same batch instead, and you sidestep the penalty of destroying a stamp you never needed. We've written about this route in more depth elsewhere. It remains our strongest recommendation for any brand still deciding how to structure its supply chain before October.

Importing retail-ready stock? Duty Stamping Only gets it moving fast

Sometimes your goods arrive finished, packaged and ready for shelf, with nothing left to do but stamp them. That's Duty Stamping Only. We apply the stamp to your retail-ready product as it passes through our bonded warehouse. That happens on a single duty-suspended movement at import, and we release the goods into the UK market from there.

It's the simplest route on this list, and the trade-off is an honest one. Because the goods arrive already finished, you don't retain the onward bonded flexibility that part-finished stock gets under UK Stamping & Finishing. For a brand that already has its packaging locked down and just needs a compliant stamp applied, that trade-off rarely matters much. Speed usually wins out instead.

Manufacturing overseas at your own factory? Overseas Stamping under Bank Guarantee closes the gap

Not every brand owner wants to outsource their manufacturing and that's a perfectly reasonable position. If your own overseas factory already holds HMRC approval, we can still help. We act as your UK duty representative and dispatch your stamps to that approved address. We carry the legal and financial liability for every stamp from the moment it leaves our custody, with the strict reconciliation that arrangement demands handled as part of the service.

This route exists for one reason. A brand with an established overseas manufacturing relationship shouldn't have to unwind it just to get compliant. You keep your factory and your existing relationship. We handle the part of the process that has to happen on UK soil.

Once it's stamped, Fulfilment & Storage takes it from there

A stamped product still needs somewhere to sit and a way to reach your customer. Our fulfilment & Storage service covers goods-in and duty-suspended storage. It also covers pick, pack and dispatch to both retailers and consumers, with returns handled from the same site. Add it onto any of the four routes above, and your stamped stock never has to leave our facility until an order actually calls for it.

If you're based overseas yourself, Import Representation gets you started

Every route above assumes someone on UK soil is registered, accounting for duty, and talking to HMRC on your behalf. If that's not currently you, Import Representation is where you start. We act as your UK representative and handle scheme registration and stamp requisition. We also run the duty accounting and manage HMRC liaison, so an overseas manufacturer or brand owner gets a compliant route to market without setting up a UK operation from scratch.

On rates: compliance shouldn't carry a premium

A stamp applied properly, on a line built for the job, tends to cost less than one bolted onto a process that was never designed for it. That holds true across all four routes above. It's a large part of why brand owners come to us for stamping, even in cases where we haven't manufactured a drop of their liquid. Ask us about rates on a readiness call. We'll talk you through what each route costs against your actual volumes, rather than a generic price list.

The trust question, answered the same way every time

Whichever route you land on, the reconciliation behind it works to the same standard. Every stamp we apply gets tied back to an HMRC dataset and a GS1-aggregated batch record. That way, your stock stands up to an audit whenever HMRC asks to see it. That discipline runs through every route in this article, and it's the same discipline we've applied since 2014, through every rule change the industry has faced so far.

Which route fits you? A quick way to check

Run through these questions, and the right route usually becomes obvious fairly quickly:

  • Does Xyfil already manufacture your range? Your stamp is already handled.
  • Do your goods arrive part-finished? UK Stamping & Finishing is your route.
  • Do your goods arrive retail-ready? Duty Stamping Only gets you there.
  • Does your own overseas factory hold HMRC approval? Overseas Stamping under Bank Guarantee closes the gap.

Layer Fulfilment & Storage onto any of those answers. Add Import Representation underneath if you're based overseas yourself.

Book the call before the routes fill up

The 1st of October is now weeks away, and every brand owner working through this decision is racing the same date. Whichever route fits your business, the sooner you confirm it, the sooner your stock moves through the process instead of sitting behind it.

Book a VPD readiness call →

Import Part-Finished, Finish in the UK: The Smartest Route to Market Under VPD

If you manufacture or source e-liquid overseas, you're about to make a decision. Get it wrong, and it's expensive to unwind. Do you ship finished, stamped, retail-ready stock straight into the UK? Or do you import it part-finished and complete the job here?

Get it wrong, and you could burn your one shot at duty-suspended flexibility. That can happen before your stock has even cleared the port. Get it right, and you keep every option open, right up to the day you release stock for sale.

1 October 2026 is closing in fast. This isn't a decision you can afford to make on assumption. Here's the case for finishing in the UK, and why the timing matters more than most import brands realise.

Why the "finished at origin" route is riskier than it looks

It feels intuitive to finish everything overseas: fill it, cap it, stamp it, box it, ship it. One clean shipment, nothing left to do at this end. Under Vaping Products Duty, that instinct works against you.

Here's the mechanic that changes everything. Once your product is packaged as finished, retail-ready goods, HMRC allows just one further duty-suspended movement. Import a fully finished, already-stamped consignment, and that single move gets used up at the border. From that point on, any repositioning triggers the duty early. So does any onward transfer, or any change of plan. You've spent your flexibility before you've sold a single unit.

There's a second risk hiding in the same decision. Duty stamps are physical, serialised, and easy to damage in transit. Ship pre-stamped stock across borders and through freight handling, and you're exposing compliance-critical packaging to real risk. Knocks, moisture and rough handling are a normal part of long-haul shipping. Damage a stamp, and you've damaged a legal requirement, not just a label.

The smarter route: import part-finished, finish here

There's a better way to structure this. It's the route we build for import and overseas brands. You manufacture the base product overseas as usual. Instead of finishing and stamping it there, you ship it to us part-finished, under duty suspension. We complete the final stages here in the UK. That means carton assembly, leaflet insertion, duty stamping, sealing and casing, all inside an HMRC-approved facility.

Three things follow from that one change:

  • Your single duty-suspended movement stays available, not spent. The goods arrive part-finished, so they haven't triggered the one-move rule yet. That flexibility stays in your hands for whatever comes next. Export, onward transfer, or simply holding stock until you're ready to release it.
  • Duty stamping happens at the safest possible point, not the riskiest. Stamps get applied in a controlled UK facility, immediately before goods are released. Not months earlier, on the other side of a container ship.
  • Your duty point lands on release, not on arrival. VPD becomes due when finished, stamped stock actually leaves duty suspension for sale. That's a timing benefit, not a reduction in what you owe. You pay the same duty either way. You simply pay it when the goods actually reach the market, rather than the day they touch UK soil.

What this actually looks like day to day

This isn't a theoretical structure. It's a standing service, and it works like this. Your part-finished product arrives at our site under duty suspension, exactly as agreed with HMRC. We take it through final assembly and duty stamping, then sealing and casing to retail-ready standard. From there, it stays in our approved store until you tell us to release it. That release schedule can be a full run, or a rolling one matched to your actual sales.

For an overseas manufacturer or brand owner, that means something simple. You get a UK-based finishing and compliance partner without building UK excise infrastructure yourself. No separate UK entity to register. No excise warehouse application of your own. No new HMRC relationship to build from scratch under deadline pressure. You bring us the part-finished product. We bring the approvals, the facility, and the finishing capability.

Why the timing on this decision is urgent right now

Every week you wait is a week closer to 1 October with the decision still unmade. Three deadlines are converging on the same date, and none of them move for anyone:

  • VPD applies from 1 October 2026, at a flat £2.20 per 10ml. That covers every UK-sold vaping product, whatever the format or nicotine strength.
  • HMRC approval takes a minimum of 45 working days. That clock is already tight for anyone who hasn't started.
  • The duty stamp grace period runs only to 31 March 2027. Any finished, unstamped stock still in the supply chain after that date becomes a live compliance problem, not a future one.

If you're currently planning to ship finished stock and stamp at origin, this is the moment to stop and rework that plan. Don't wait until your next shipment is already at sea. Switching the structure of an import route takes coordination on both sides. That coordination only gets harder the closer you get to October.

The question to ask before your next shipment

Before you finalise your next order with an overseas manufacturer, ask one question. Will this shipment use up your one duty-suspended movement before it's even reached a UK customer? If the honest answer is yes, talk to us before that shipment leaves, not after.

We handle the UK side of this route for import brands and overseas manufacturers every day. Duty-suspended receipt, finishing, stamping, storage, and release timed to your actual sales. Want to talk through whether your current import route is spending flexibility you don't need to lose? Book a call or get in touch. We can also walk you through our current approvals and compliance credentials directly. Just ask.

Importer of Preference: How an Excise Warehouse Handles Your Imports

If you import finished e-liquid into the UK, Vaping Products Duty changes your position more than most. The duty makes the importer liable, and it lands the moment your stock enters the UK market. So the way you bring stock in — and where it sits once it arrives — suddenly shapes your cash flow and your compliance. Let's walk through the smarter route.

What importing actually triggers

Under VPD, you carry the duty liability as the importer. You're not a passenger in someone else's supply chain — you're the accountable party, and that means registering with HMRC before you can lawfully bring vaping liquid into the country.

If you import product on behalf of an overseas manufacturer, the rules ask even more of you. You may need to act as their UK representative. That role carries real weight: you apply for approval on their behalf, and you buy the duty stamps too. HMRC looks to you, not the factory abroad, as the accountable party on UK soil.

Here's the point that catches people out. Importing doesn't dodge the duty. It simply decides who accounts for it — and, quite often, that's you.

From 1 October 2026, only two routes stay open for imported stock. Either it arrives already carrying a valid duty stamp, or it enters through an approved duty-suspension arrangement. Every other route closes on that date. That's a hard compliance line, not a soft recommendation, so it's worth mapping now rather than scrambling in September.

Bring stock straight onto the open market without either safeguard, and the duty falls due immediately. That's the expensive way to do it. You fund the full duty bill the moment the container lands, long before a single unit reaches a customer, and there's no way to claw that timing back once it's happened.

The excise-warehouse alternative

There's a calmer route. Instead of landing stock straight into the market, you bring it into an approved excise warehouse, where it sits in duty suspension. The duty point then waits until the goods are released for UK consumption — not the day they arrive.

Two mechanics make this work. First, an approved warehouse can legally hold duty-suspended stock, so nothing forces an early release. Second, that stock moves under EMCS, the system HMRC uses to track duty-suspended goods as they travel. Together, they let your imported stock wait, compliantly, until you genuinely need it.

And the same rule applies at the edges as it does everywhere else in VPD: stock you export onward, or destroy under bond, doesn't attract UK duty at all. You only ever pay on what genuinely enters the UK market.

Timing, not a discount

Let's keep this honest, because it matters. Holding imported stock in duty suspension doesn't reduce the duty on anything you eventually sell in the UK. If every unit releases to UK customers, the total bill stays the same. What changes is the timing: you pay as you release, not as you land. That's a genuine cash-flow advantage, and a legitimate one. It is not a way around the duty, and no manufacturer should pitch it to you as one.

How we can sit in the middle

This is where an excise warehouse earns its keep. We operate an approved bonded warehouse, so your imported stock can arrive and sit with us, duty-suspended, moving under EMCS until you choose to release it. In effect, our facility becomes the buffer between the port and the point of sale.

Our HMRC VPD approval is now granted, and our operations team has signed off the process end-to-end. Our credentials page, where you'll see the full detail, is launching soon. Until it does, we're happy to talk you through exactly where things stand today and what we can already carry for you.

Become the importer of preference

The brands that get this right won't scramble in September. They'll have a route mapped, a warehouse arranged, and their duty timed to their sales. If you import finished e-liquid, that's the position worth aiming for.

Common questions from importers

Do I need my own HMRC approval if I import finished e-liquid?

Usually, yes. As the importer, you're the liable party under VPD, so you register with HMRC yourself. If you bring product in for an overseas manufacturer, you may also take on the UK representative role, which brings its own approval and stamp-buying duties.

Does using a bonded warehouse remove my compliance obligations?

No. A warehouse changes when duty falls due, not whether you're registered and accountable. A partner can hold your stock duty-suspended and manage the storage and movement side, but the underlying registration still sits with whichever party the rules point to.

What happens if my stock arrives without a valid duty stamp?

From 1 October 2026, unstamped stock has to enter through an approved duty-suspension route rather than straight onto the open market. Arriving any other way risks falling foul of the rules, so confirm your route before you ship, not after.

Can I still import stock if I plan to export part of the shipment onward?

Yes. Stock you export onward, or destroy under bond, doesn't attract UK VPD at all. Only the portion that genuinely enters the UK market gets taxed.

So let's map your import route before the deadline sets it for you. Let's discuss - get in contact today.

Give Us Your Headache: What You Stop Paying For With a Managed Service

Vaping Products Duty doesn't just add a line to your costs. It adds a whole job. Approval, returns, stamps, storage, records — someone has to run all of it, every month, without slipping. So the real question for a brand owner isn't only "what does the duty cost?" It's "who's going to carry the work?"

Here's what that work actually looks like — and what you stop carrying when a managed partner takes it on.

The admin VPD quietly hands you

Go it alone, and this list becomes your day job.

  • Approval. You apply to HMRC and wait — potentially upwards of 45 working days — before you can lawfully release stock.
  • Monthly returns. You calculate the duty, file on time, and pay on time, month after month. Miss a deadline and penalties follow.
  • Duty stamps. You buy them from the appointed supplier, affix them correctly, and handle the scanning and records that come with the digital ones.
  • Duty-suspended storage. You either pay the duty up front, or you arrange approved storage so the duty waits until release.
  • Audit trails. You keep detailed records of every batch, every movement, and every stamp — ready for HMRC to inspect.
  • Precision on fill. Because duty tracks volume, every millilitre of over-fill is duty you've simply thrown away.

None of it is optional. All of it takes time, systems, and people. And every hour spent on excise admin is an hour not spent growing your brand.

What a managed partner absorbs

Now flip it. When you manufacture with a partner built for this, most of that list stops being yours.

We hold your stock in our approved bonded warehouse, so it sits duty-suspended until it ships. We run the batch tracking and the audit trails HMRC expects. We handle the stamps and the precision filling that stops duty leaking through waste. In short, the excise machinery becomes our problem, not yours.

That's the idea behind "give us your headache." You keep the parts of the business only you can do — the brand, the range, the customers. We take the parts that are pure operational drag.

Over a decade of doing exactly this

We've manufactured for hundreds of UK brands since 2014. So the systems that VPD now demands — records, storage, quality control, precise filling — aren't new to us. They're what we already run, every day, at scale. VPD simply adds a new layer, and we've built for that layer too.

That experience matters most in the moments that go wrong. A missed return, a mislabelled batch, a stamp error — each is a small crisis for a brand handling it alone. For a partner who does this daily, it's just process.

We said we'd tell you when it landed

We always said we'd be straight about where our approval stood. So here it is, confirmed in writing. Xyfil now holds HMRC approval for Vaping Products Duty, alongside our approved bonded warehouse. We can produce lawfully, hold your stock duty-suspended, and release it duty-paid as it ships.

That matters more than it sounds. Approval isn't quick — anyone applying now waits at least 45 working days before they can release stock. Partner with us and you skip that queue. You're not starting from zero.

Ready to hand it over?

If the VPD admin already feels like a second job, that's the signal. Let us show you which parts of it you can simply put down.

Hand us the headache →

Who Needs HMRC Approval, and What Happens If You’re Not Approved

The single most common Vaping Products Duty question we hear from brand owners is a simple one: "Do I need HMRC approval, or does my manufacturer handle that?" It's a fair thing to ask. And the answer decides who carries the risk on 1 October. So let's clear it up properly.

First, the rule HMRC actually applies

Approval follows the activity, not the name on the bottle. HMRC approves the business that manufactures, imports, or holds the stock — not simply whoever sells it to consumers. So your obligation depends entirely on how your product reaches the market.

One date makes this urgent. From 1 October 2026, it's against the law to manufacture vaping liquid in premises HMRC hasn't approved. That even includes mixing non-duty-paid liquids to make a finished product. In other words, "producing" is defined broadly, and unapproved production simply isn't allowed.

Three routes, three very different obligations

Most brands fall into one of three groups. Find yours below.

If you manufacture your own liquid

Then the obligation is yours, full stop. You apply to HMRC for approval, you buy and affix duty stamps, you file returns, and you carry the compliance day to day. There's no way to hand that off while you run your own production.

If you import finished e-liquid

Then you're liable for the duty, and you must register. And if you act as the UK representative for an overseas manufacturer, that responsibility sits squarely with you. Importing doesn't sidestep approval — it simply changes which approval you need.

If you use a UK manufacturer

Here the load gets lighter. When a UK manufacturer produces and releases your stock as the approved producer, the production-approval obligation sits with them, not with you. You still own your brand's side — your labelling, your records, and your choice of a genuinely approved partner. But you don't have to hold producer approval yourself.

What happens if you're not approved

The answer is simple, and it's serious. Without approval, you can't lawfully release duty-paid stock. You can't buy duty stamps either. And you can't manufacture in unapproved premises. Put those together, and the result is stark: no lawful route to market on 1 October.

Timing makes it sharper still. Approval isn't instant — HMRC warns it can take upwards of 45 working days. So if you apply late, you could sit unable to trade while the clock runs down. That's the real deadline hiding behind the headline one.

The quiet risk for outsourced brands

Even if you outsource everything, one duty stays with you: choosing a partner who is genuinely approved. If your manufacturer isn't approved in time, their problem quickly becomes your empty shelves. So the question isn't only "do I need approval?" It's also "can I prove my manufacturer has it?"

That's a fair thing to ask any supplier directly. A partner who can't answer clearly is a partner who leaves you exposed.

Where we fit in

We're HMRC-approved for VPD, so we can carry the production burden for the brands we manufacture for. That's the whole point of a managed partner. You focus on building your brand, while your manufacturer handles the approval, the stamps, the returns, and the stock.

So if you're not sure which of the three routes you're on — or whether your current setup leaves a gap — let's talk it through before the 45-working-day window makes the decision for you.

Speak to the team →

The £2.20 Trap: What Volume-Based Duty Does to a Stockpiled Warehouse

With October approaching, plenty of brand owners share the same instinct: build up stock now, before the duty lands. It feels sensible. Get ahead of the deadline, fill the warehouse, and ride out the change. Yet that instinct hides a trap — and the trap has a number on it. That number is £2.20.

Here's the problem in one line. Vaping Products Duty is volume-based, so a stockpiled warehouse turns that small-looking rate into a very large bill you pay long before your stock sells. Let's walk through why.

£2.20 looks small. At volume, it isn't.

From 1 October 2026, VPD adds £2.20 per 10ml to every UK e-liquid. That works out at 22p per millilitre. It applies whether your liquid carries 20mg of nicotine or none at all, because the duty tracks volume, not strength.

On a single bottle, the rate feels minor. Across a production run, though, it stacks up fast. A 2ml pod carries 44p in duty. A 10ml bottle carries £2.20. Multiply either by a warehouse full of stock, and the total climbs into six figures quickly. So the rate isn't really the threat. The volume is.

A full warehouse is a committed duty bill

Now picture the stockpiling plan in practice. You forecast a strong Q4. You produce a big run ahead of October. Then you hold it, finished and ready to ship.

Here's the catch. To keep finished, duty-paid stock sitting ready, you have already paid the duty. Say you build 500,000 2ml pods. At 44p each, that's £220,000 in duty — committed before a single pod reaches a customer. Your cash has left the business. Your stock, meanwhile, has not.

That's the trap. A stockpiled warehouse doesn't just hold product. It holds a tax bill you've already settled, on goods that haven't earned a penny yet.

Volume-based duty punishes the wrong stock

The trap bites hardest on slow movers. Think it through. You pay to store that stock. On top of that, you've fronted the duty on it. So a line that sells slowly costs you twice — once in storage, and once in duty you paid months too early.

Fast-selling lines recover quickly. Slow ones simply sit there, tying up cash you could spend on marketing, new formats, or your next launch. In short, the more you stockpile, the more working capital you freeze.

The duty point is your way out

Now for the good news. VPD doesn't attach to stock the moment it exists. Instead, it attaches at a trigger called the duty point. For most brands, that trigger fires when finished liquid leaves duty suspension for sale in the UK.

That single detail changes everything. If your stock waits in a duty-suspended state, the duty waits with it. You stop paying tax ahead of sales, and the bill starts to track your shipments instead. So the smart move isn't to stockpile duty-paid stock. It's to hold your stock so the duty falls due as you sell.

Two ways to hold stock without the trap

A managed manufacturing partner can hold your stock in a state that defers the duty point. In practice, there are two routes.

Route one: a bonded warehouse

Produce your full run, then hold the finished stock in a bonded warehouse. It sits duty-suspended until it ships. Order 20,000 units, release 10,000 to meet real orders, and duty falls due on those 10,000 — not on the full run. The remaining 10,000 simply wait in bond until you need them.

Better still, any stock you export or destroy under bond never attracts UK duty at all. So you only ever pay duty on what genuinely enters the UK market.

Route two: component form

Sometimes you don't need finished stock yet. In that case, a manufacturer can hold your ingredients — flavour concentrate, base and nicotine — stored separately. Unblended, they aren't vaping liquid, so they carry no duty. They are then blended and package to order, so the duty applies only on the volume you release.

Either way, your duty bill follows your sales rather than your production schedule.

This is timing, not a loophole

Let's be clear on one point, because it really matters. Neither route reduces the duty you owe on stock sold in the UK. If all your held stock eventually ships to UK customers, the total duty ends up exactly the same. You've simply paid it as you sold, not before.

That distinction is what keeps you safe. "Avoiding the duty" isn't a strategy — it's a fast route to a difficult HMRC conversation. Protecting your working capital by lining the duty point up with your sales, on the other hand, is completely legitimate. That's precisely what a bonded warehouse and component-form storage are built to do.

One more compliance detail is worth knowing. Once you package products for retail, HMRC allows just one move in duty suspension. Further movements trigger the duty early, so movement planning matters — another reason to lean on a partner who handles this every day.

Questions to ask before you fill a warehouse

Before you commit to a stockpiling plan, or to any manufacturer, put these questions on the table:

  • If I hold finished stock, is it duty-suspended in an approved bonded warehouse — or am I paying duty up front?
  • Can you hold my stock in component form and blend to order?
  • How do you plan stock movements so I don't trigger the duty early?
  • What batch tracking and audit trails will I get for HMRC?

Clear answers protect your cash. Vague ones leave you carrying the risk.

See your own number before October

Every brand's exposure looks different, because formats, volumes and release schedules all shift the maths. So before you build a single extra pallet, model your position first. Our VPD calculator shows what a stockpiled run would cost you up front — and what changes when the duty tracks your shipments instead.

Model your duty exposure with our VPD calculator →

The 45-Day VPD Bottleneck: How HMRC Approval Works — and Who It Applies To

On 1 October 2026, Vaping Products Duty goes live at 22p per ml - that's £2.20 per 10ml bottle of e-liquid. Alongside it, the Vaping Duty Stamps Scheme changes how vaping products are made, marked, and released. Every business in the supply chain needs to be ready.

But before any of that, one step comes first. To make, import, stamp, or release duty-paid vaping products, you need HMRC approval. And that approval takes time. HMRC warns it can take at least 45 working days, and longer if they need more information.

That waiting period is what the industry now calls the 45-day VPD bottleneck. Here’s how the process works, who it applies to, and why the timing matters so much.

What is the 45-day VPD bottleneck?

It’s simpler than it sounds. Approval isn’t automatic, and it isn’t instant. Applications opened on 1 April 2026, and HMRC processes each one in turn. The checks take at least 45 working days. So businesses that apply late risk missing approval before the duty goes live.

Now do the maths. Count back 45 working days from 1 October, and the practical deadline to apply lands in mid-summer, not September. Miss it, and your application may still sit in the queue on go-live day.

The stakes are high, too. Without approval, you cannot lawfully produce, import, or release duty-paid stock. So this isn’t just paperwork. It’s the gate that decides whether you can trade from October.

What the approval process actually involves

HMRC approval is thorough by design. First, you apply as a single legal entity. That means one business, controlled and managed as a single unit for tax purposes. Then you submit a business plan and a plan of your premises, along with your security arrangements and expected volumes.

In some cases, HMRC also asks for a financial guarantee. This is common for newer businesses, or where there’s a history of tax issues. Each request for more detail adds days, so a tidy, complete application moves faster.

Clearly, this isn’t a form you dash off in September. It’s a process that rewards early, careful preparation.

Who needs approval: manufacturers, importers, and brand owners

Here’s where many businesses get confused. The rules apply differently depending on how you bring your products to market. So let’s break the three main cases down clearly.

If you manufacture your own liquid

If you produce vaping liquid in the UK, the obligation sits squarely with you. You must hold HMRC approval for both VPD and the Vaping Duty Stamps Scheme before 1 October 2026. From that date, producing on unapproved premises becomes an offence, and that includes mixing non-duty-paid liquids. You also calculate and pay the duty, and you attach a duty stamp to every retail pack before release. And if you want to store stock before the duty is paid, that storage site needs approval for duty suspension too.

If you import finished products

If you import finished vaping products, you carry the duty liability. From 1 October 2026, you can’t import an overseas manufacturer’s products without duty stamps attached. The one exception is stock going straight into HMRC-approved duty-suspension premises. Overseas manufacturers must appoint an approved UK representative to order and apply those stamps. In practice, that representative is often the importer. So if you import, you either need approval yourself or a clear, approved route to get stamps on your products first.

If you use a third-party manufacturer

Here’s where many brand owners feel unsure. If you own the brand but outsource production to a UK manufacturer, the production approval usually sits with that manufacturer, not with you. In other words, you rely on your manufacturer’s approval to reach the market compliantly. That makes one question business-critical: is your manufacturer approved, or on track to be? If they’re stuck in the queue, so are you. Your exact obligations still depend on your setup, such as who owns the stock and who releases it. So it’s worth confirming your position with HMRC or an adviser. As a rule, though, the right partner carries the heavy compliance load for you.

The VPD timeline you should know

The rules roll out in clear stages, and each one tightens the window. Here’s what HMRC has confirmed.

  • 1 April 2026 — Approval and registration open. You need approval before you can buy stamps, produce or import duty-paid stock, or file returns.
  • 1 April – 31 August 2026 — Transitional duty stamps carry physical security features only, and approved businesses can buy them.
  • From September 2026 — Duty stamps gain digital features for traceability.
  • 1 October 2026 — VPD applies at £2.20 per 10ml, and retail packs must carry a duty stamp.
  • 1 April 2027 — The sell-through period for older stock ends, so every product outside duty suspension must carry a duty stamp.

Notice the squeeze. Approval opened in April, but it isn’t instant, and the duty bites in October. With a 45-working-day minimum, every week you delay eats into your margin for error.

What VPD means for your costs and margins

The duty itself is simple to state but significant to absorb. From October 2026, every 10ml of e-liquid carries £2.20 in duty, whatever the nicotine strength. So a 100ml shortfill, for example, attracts £22 in duty before you add production, packaging, and margin.

That reshapes your pricing, your cash flow, and your stock planning all at once. Therefore, the businesses that model it early can adjust formats, pack sizes, and price points calmly. By contrast, those that leave it late tend to react under pressure and erode their own margins.

How Xyfil helps you get ready

This is where a prepared partner makes the difference. Xyfil is a UK manufacturer and producer of e-liquids, nicotine salts, CBD, and personal care products, and we’ve supported hundreds of UK brands. Like every UK producer, we’re preparing for VPD and working through the approval process, so we know the requirements inside out.

Our GMP and ISO-certified facilities produce up millions of products every month across ISO 7 clean rooms. That scale lets us absorb demand smaller operators simply cannot. Need bottling for an existing range, or a brand built from scratch? Our white label service moves you from idea to shelf quickly.

Compliance is where many brands stumble, so we made it a strength. Our 6-stage compliance process keeps you aligned with UK, EU, and Middle East requirements, and our team lives and breathes traceability and testing. And we've been here before keeping up with the regulation changes and moving to adapt to ensure our partners don't feel the pinch. So we turn the VPD transition into a managed, predictable plan.

What to do right now

You don’t need to solve everything today. You do, however, need to act on the step with the longest lead time. Here’s a simple order of priority.

  • First, work out which category you fall into. Do you manufacture, import, or outsource? Your obligations flow from that answer.
  • Second, if you make or import yourself, apply for approval as soon as you can, because the 45-working-day clock won’t wait.
  • Third, consider whether you need to carry all of that yourself. If you manufacture in-house or import finished stock, you have another option. You can lighten the load by moving production to a UK contract manufacturer. Hand production to a partner like Xyfil, and the heavy lifting shifts across with it. The premises approval, the duty sums, the stamping, and the record-keeping become your manufacturer’s job, not yours. So a daunting compliance checklist becomes one managed relationship.
  • Fourth, if you outsource, ask your manufacturer a direct question. Are you approved, or on track for approval before October?
  • Fifth, map your products against the stamp timeline so nothing stalls at the final hurdle.

Talk to Xyfil about your VPD readiness

The 45-day bottleneck is coming, but it doesn’t have to catch you out. With the right partner and a clear plan, the VPD transition becomes just another well-run project.

Get in touch with Xyfil to talk through your route to 1 October 2026. The earlier you start, the smoother your transition.

Frequently asked questions

What is the 45-day VPD bottleneck?

It’s HMRC’s approval window. Before you can produce, import, stamp, or release duty-paid vaping products, HMRC must approve you first. That takes at least 45 working days, sometimes longer. Apply too close to 1 October 2026, and your approval may not come through in time.

Who needs HMRC approval?

UK manufacturers, importers, and warehousekeepers all need approval to keep trading under VPD. Overseas manufacturers must appoint an approved UK representative, who is often the importer.

I use a third-party manufacturer, so do I need my own approval?

Usually, the production approval and duty stamping sit with your manufacturer. So a pure brand owner often doesn’t need their own producer approval. It does depend on your arrangement, such as who owns and releases the stock, so confirm your position with HMRC or an adviser.

When does Vaping Products Duty start?

VPD applies from 1 October 2026 at £2.20 per 10ml of e-liquid, nicotine or not. Approval opened on 1 April 2026, and every product outside duty suspension must carry a duty stamp by 1 April 2027.

1 2 3 … 5